A pre-approval estimates how much you can borrow and may include a rate lock, while a rate hold only protects an interest rate for a set period. Both are conditional, and neither guarantees final funding, as the FCAC and CMHC both make clear. Get pre-approved early, then add a hold once your timeline firms up. We at DreamHouse Mortgage can help you do both.
TL;DR:
- Rate holds usually last 60 to 130 days; ask about extensions and whether a float down lowers your rate if market rates fall.
- Prepare photo ID, income records, bank statements, down payment proof, and asset and debt details; self employed borrowers and newcomers may need extra documents.
- Federally regulated banks qualify borrowers at the higher of 5.25% or the negotiated rate plus 2%; credit unions may use different standards.
- Compare lenders on term, fixed or variable structure, prepayment privileges, penalties, portability, and total borrowing cost, not just the advertised rate.
Table of Contents
- What is a pre-approval, and what is a rate hold in Canada?
- How do protections and limits compare?
- How long do holds last, and what documents do you need?
- How does the stress test affect a held rate?
- When should you use a pre-approval, a rate hold, or both?
- Why do we pair a pre-approval with a rate hold for Alberta buyers?
- Ready to get pre-approved in Calgary?
- FAQ
- Sources
What is a pre-approval, and what is a rate hold in Canada?
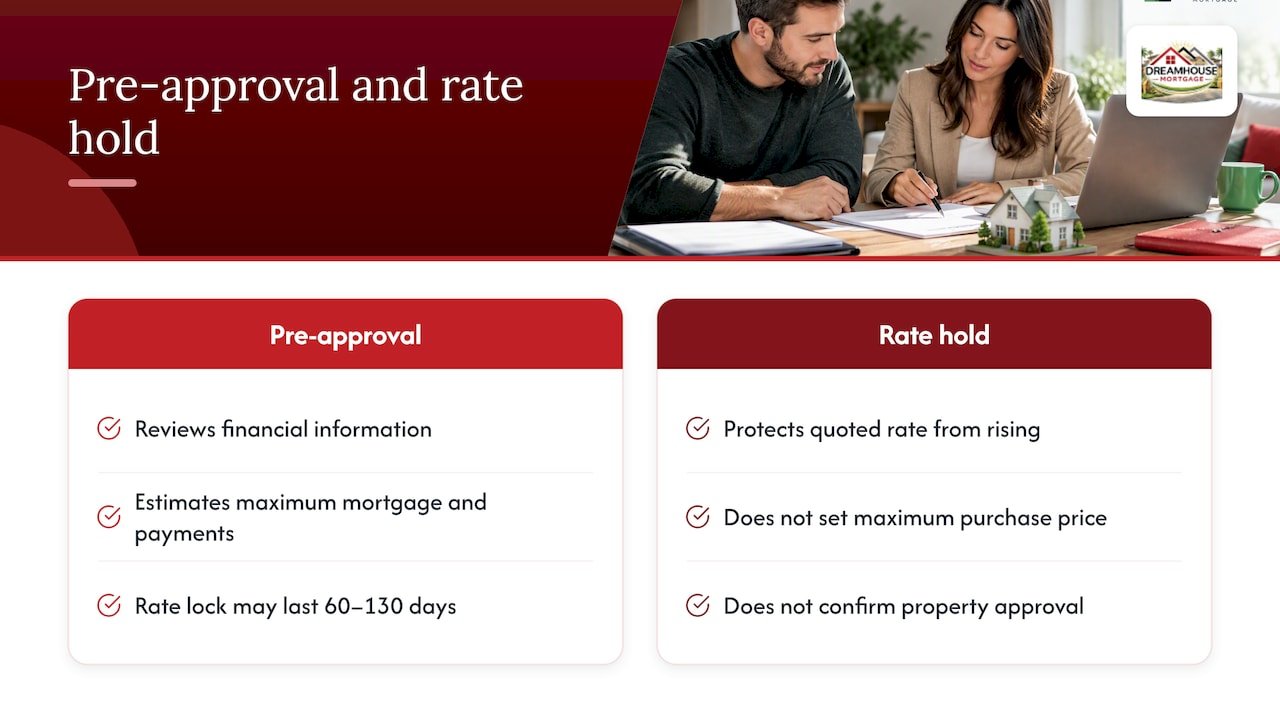
A pre-approval is a lender’s early review of your finances. It normally assesses your financial information, estimates the maximum mortgage amount and payments you could carry, and may lock an interest rate for 60 to 130 days, depending on the lender. Lenders use different labels for this step, including pre-qualification and pre-authorization, so always ask what was actually reviewed and what remains conditional.
A rate hold is narrower. It keeps the quoted rate from rising during the lender’s stated validity period. It does not set your maximum purchase price, prove a property is acceptable, or remove the need for final underwriting.
Then there is the float-down, sometimes called a best-rate feature. It decides whether you automatically receive a lower rate if market rates fall while your pre-approval is active. Not every lender offers one, so ask before you rely on a hold.
If you are a first-time buyer in Calgary, our mortgage pre-approval service walks you through the first step.
How do protections and limits compare?
Think of it as three questions: what is protected, what is signaled, and what can still change.
A hold protects price. A pre-approval signals buying power, which helps when a seller in Airdrie or Cochrane is deciding whether to take your offer seriously. Neither removes final underwriting risk. Final approval still depends on verifying your income, credit, down payment, property details and appraisal, plus any lender conditions.
What typically stays conditional after a hold or pre-approval:
- The appraisal of the property
- Whether the lender accepts the property itself
- Verification of your income and documents
- Your credit profile at the time of final approval
Before you rely on either, ask your lender or broker:
- How long is the rate guaranteed, and can the hold be extended?
- Is there a float-down or best-rate feature?
- What did you verify, and what is still conditional?
- Does the pre-approval include a rate lock at all?
Pro Tip: Document your income early. Gather pay stubs, T4s and, if you are self-employed, tax filings before you shop, so a missing page does not change your approval later.
Our rate hold page for Calgary buyers explains how we approach locking a rate locally.
How long do holds last, and what documents do you need?
Expect a validity window of roughly 60 to 130 days, depending on the lender. If your deal slips past the expiry date, ask whether the lender will extend the hold. If not, you may need to reapply, and your rate and qualification could change.
Incomplete paperwork is a bigger threat than most buyers expect. CMHC says incomplete or missing information is the most common reason for mortgage approval delays. Requirements vary by lender, so confirm your list first.
Have these ready:
- Government-issued photo ID
- Employment and income proof, such as a job letter, recent pay stubs and T4s
- Bank statements and proof of your down payment
- A summary of your assets and debts
- Property details, if you have already chosen a home
Self-employed borrowers and newcomers to Canada may need additional documentation, so start earlier. Our Alberta documents checklist breaks down what each situation typically requires.
How does the stress test affect a held rate?
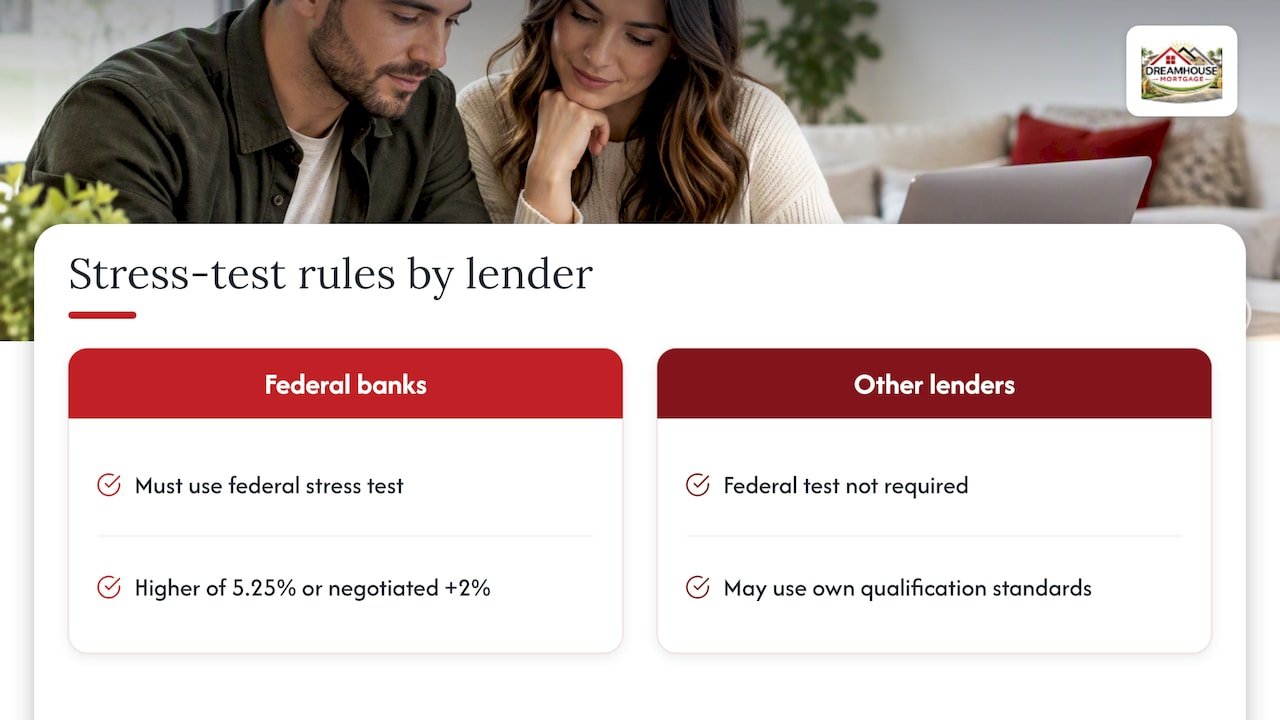
A held rate protects your price, but it does not change how you qualify. For federally regulated banks, the qualifying rate is the higher of 5.25% or the negotiated rate plus 2%. That qualifying rate is separate from the contract rate you are holding.
In practice, your monthly payment may look comfortable at the held rate, yet you still must show you could carry the debt at the higher qualifying rate. That is why a hold and affordability are different questions. Credit unions and other non-federally regulated lenders do not have to use the federal stress test, although they may apply their own qualification standards.
When you compare options, ask your broker which qualifying rate each lender uses. Doing this before you shop keeps you from falling in love with a home in Chestermere or Okotoks that your qualifying numbers will not support. Our guide to Canadian mortgage rates covers how contract and qualifying rates differ.
When should you use a pre-approval, a rate hold, or both?
Use this checklist to decide:
- Get pre-approved early, ideally before you tour homes, to set a realistic budget and strengthen your offers.
- Add a rate hold when your closing timeline is firm or when rates are rising and you want price protection.
- If the market feels uncertain, ask about float-downs and extension options before leaning on a hold.
- In Calgary, Airdrie and Cochrane, a pre-approval can help you understand your budget before making an offer.
Compare more than the headline rate. FCAC advises looking at term, fixed versus variable structure, prepayment privileges, penalties, portability and total cost of borrowing.
Pro Tip: Do not let a hold’s start date run before you are ready to make offers. A hold that expires while you are still browsing protects nothing.
First-time buyers can read our first-time home buyer guide for Calgary for more on timing.
Why do we pair a pre-approval with a rate hold for Alberta buyers?
A practical approach is to treat the pre-approval as your starting line, and the hold as a deadline tool. A pre-approval tells you what is realistic. A hold only earns its place once you know roughly when you will buy.
For first-time buyers, we usually suggest calling us before you start touring Calgary communities, so your documents are in order while the pressure is low. Then, once your search narrows, we look at whether a hold fits your timeline. Bring your documents, ask the questions above, and call us.
— Guriqbal Chahal, MBA, PMP
Ready to get pre-approved in Calgary?
We help buyers across Calgary, Airdrie, Cochrane and surrounding Alberta communities explore pre-approvals and rate holds. We also help you prepare your documents so your file moves quickly.
Here is how we can help you start:
- Review your income, down payment and credit with you
- Compare lenders for the pre-approval and hold terms that suit your timeline
- Prepare your document package so approval is not delayed
Call Guriqbal Chahal, MBA, PMP, Mortgage Broker at 403-966-6072, or request your mortgage pre-approval in Calgary. You can also see what clients say on our Google Business Profile.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Do pre-approval letters include interest rates?
Often they do, but it depends on the lender. A pre-approval may lock a rate for a set period, usually 60 to 130 days. Ask whether your letter includes a rate lock and whether it can be extended.
How early should I lock in my mortgage rate?
Lock once your purchase timeline is reasonably firm, so the hold does not expire before you close. If you are still months from buying, a pre-approval alone may be enough. Ask your broker about float-down options first.
Does a rate hold guarantee my mortgage?
No. A hold protects the rate, but final approval still depends on verifying your income, credit, down payment and the property. Missing information is a common cause of delays.
What interest rate can I expect?
Your rate depends on your term, fixed or variable choice, credit history, employment status and lender. FCAC notes that rates vary by lender, so comparing several is worthwhile. We can compare options for you.
Sources
Recommended
- Preapproval vs Approval: Calgary Appraisals Can Change the Deal
- Bank of Canada Rate Calgary Mortgage: How the Bank of Canada Rate Affects Your Calgary Mortgage | Critical Insights for Homebuyers
- Mortgage Pre-Approval Process Explained for Alberta Buyers
- Mortgage Approval Time Calgary: How Long It Really Takes & How to Speed It Up