If you are comparing mortgage broker options, DreamHouse Mortgage is a direct, local alternative you can contact today for first-time buyer mortgages, pre-approvals, refinancing, and renewals. Beyond an independent broker like this, your realistic paths include a bank mortgage advisor, a credit union advisor, an online mortgage platform, or a private lender. Call Guriqbal Chahal, MBA, PMP, Mortgage Broker, at 403-966-6072 to start a consultation.
TL;DR:
- A mortgage broker offering access to banks, credit unions, monoline, and private lenders can better serve complex income profiles and urgent needs than a single online platform.
- If you already bank at a financial institution with straightforward income, a bank or credit union advisor might suffice, but they limit options to one lender’s products.
- Federal mortgage stress tests and recent program reforms significantly influence your maximum purchase price, making provider experience with these rules crucial.
- Choosing a provider who clearly explains lender options, stress-test implications, and necessary documentation can save time and improve your qualification chances.
- Gathering all relevant income, down payment, and identification documents before your first call speeds up approval and helps prevent delays.
Table of Contents
- Comparing your practical alternatives to a single-broker site
- How to choose and what to ask on the first call
- What actually matters when you compare these routes
- Start your mortgage conversation with DreamHouse Mortgage
- Sources
- FAQ
Comparing your practical alternatives to a single-broker site
A full-service mortgage brokerage worth considering is one led by an experienced broker with access to banks, credit unions, monoline lenders, and private lenders. It suits first-time buyers who want one person managing the paperwork, the lender search, and the qualification math, plus borrowers with self-employed or nonstandard income who need a lender willing to look past a standard pay stub.
A bank mortgage advisor works for a single lender. If you already bank there and your income and credit fit that lender’s criteria cleanly, this route can feel simple because the advisor already has your account history. The trade-off is that you only see that bank’s own products and rates, with no comparison across the market.
A credit union advisor operates similarly but through a member-owned institution. Credit unions often set their own underwriting rules rather than following federally regulated lender guidelines, which can matter for how your file gets assessed. Service tends to be relationship-driven, and some credit unions are not bound by the same federal stress-test framework that applies to banks.
An online mortgage broker or aggregator platform digitizes the rate-shopping process. You fill out a profile and get matched with lenders or rate quotes quickly, which works well if your income, credit, and down payment are straightforward. More complex files (self-employed, new to Canada, multiple properties) usually need a human conversation that a form cannot fully capture.
A private lender steps in when conventional underwriting says no, whether due to credit history, income documentation, or timeline pressure. Rates and fees run higher than bank or broker-sourced mortgages, but private lending can bridge a gap when nothing else will close in time.
| Option | Best for | Services offered | Lender access | Typical approval speed |
|---|---|---|---|---|
| DreamHouse Mortgage | First-time buyers and complex income files needing broad lender comparison | First-time buyer, pre-approval, refinancing, renewal, self-employed, private lending | Banks, credit unions, monoline, private | Days to about two weeks depending on documentation |
| Bank mortgage advisor | Existing bank customers with straightforward income and credit | Standard mortgage products from one lender | Single bank only | Varies by branch workload |
| Credit union advisor | Buyers who prefer member-owned, relationship-based underwriting | Standard and some flexible products | Single credit union | Varies by institution |
| Online broker/platform | Tech-comfortable borrowers with simple, clean files | Rate comparison and digital applications | Multiple lenders via platform | Fast for simple profiles |
| Private lender | Borrowers conventional lenders decline, or urgent closings | Short-term and alternative financing | Private capital sources | Can be fast, often days |
A few situations point clearly toward one path over another:
- A self-employed buyer with variable income often qualifies more easily through a broker who can place the file with a lender that accepts add-back income.
- A buyer who needs funding within days and has exhausted conventional options may need a private lender despite the higher cost.
- A buyer loyal to one bank with a simple T4 income and strong credit may find a bank advisor’s process perfectly adequate.
- A buyer comparing multiple lender rates quickly, with no complications, can reasonably start with an online platform.
Pro Tip: Recent federal changes, including the Tax-Free First Home Savings Account and a higher Home Buyers’ Plan withdrawal limit, mean a broker who actively applies the newest first-time buyer rules, including wider access to 30-year insured amortizations, can matter more than the lender name on your mortgage.
How to choose and what to ask on the first call
Pick a provider using a short checklist rather than a gut feeling:
- Confirm the lender panel size: ask how many lenders they work with and whether that includes credit unions and monoline lenders, not just one or two banks.
- Ask about first-time buyer program knowledge, specifically the Home Buyers’ Plan and First Home Savings Account rules.
- Ask how they help you pass the federal mortgage stress test, which requires qualifying at the higher of 5.25% or your rate plus 2% for federally regulated lenders.
- Ask directly about fees: whether you pay anything out of pocket or the lender pays their commission.
- Ask what documents they need up front and whether they help assemble income and down payment proof.
On the call itself, ask plainly: “Which lenders do you use for first-time buyers?” and “How fast can I get a pre-approval?” and “Do you charge broker fees, or are you paid by the lender?” A provider who answers these without hesitation is giving you what you need to compare options fairly.
Treat vague answers as a signal to keep asking rather than a dealbreaker: if someone cannot name even a couple of lenders or dodges the fee question, ask for specifics again before moving forward. Prefer a provider who explains the stress test and walks you through the FCAC Mortgage Qualifier Tool rather than one who glosses over qualification math.
A typical pre-approval takes a few days once your documents are in, with full funding timelines running one to two weeks for straightforward purchases. Have ready: recent pay stubs or two years of tax returns if self-employed, a government ID, bank statements showing your down payment source, and your current debt obligations. Before you make an offer, a pre-purchase home inspection checklist is worth reviewing alongside your financing steps.
Pro Tip: Gather your documents before the first call. A provider can only move as fast as the paperwork you hand them.
What actually matters when you compare these routes
The conventional advice tells buyers to chase the lowest advertised rate across every platform, but rate alone misses what determines whether your deal closes on time. Lender fit, meaning whether a lender’s underwriting rules match your income type and down payment source, decides more outcomes than a quarter-point difference.
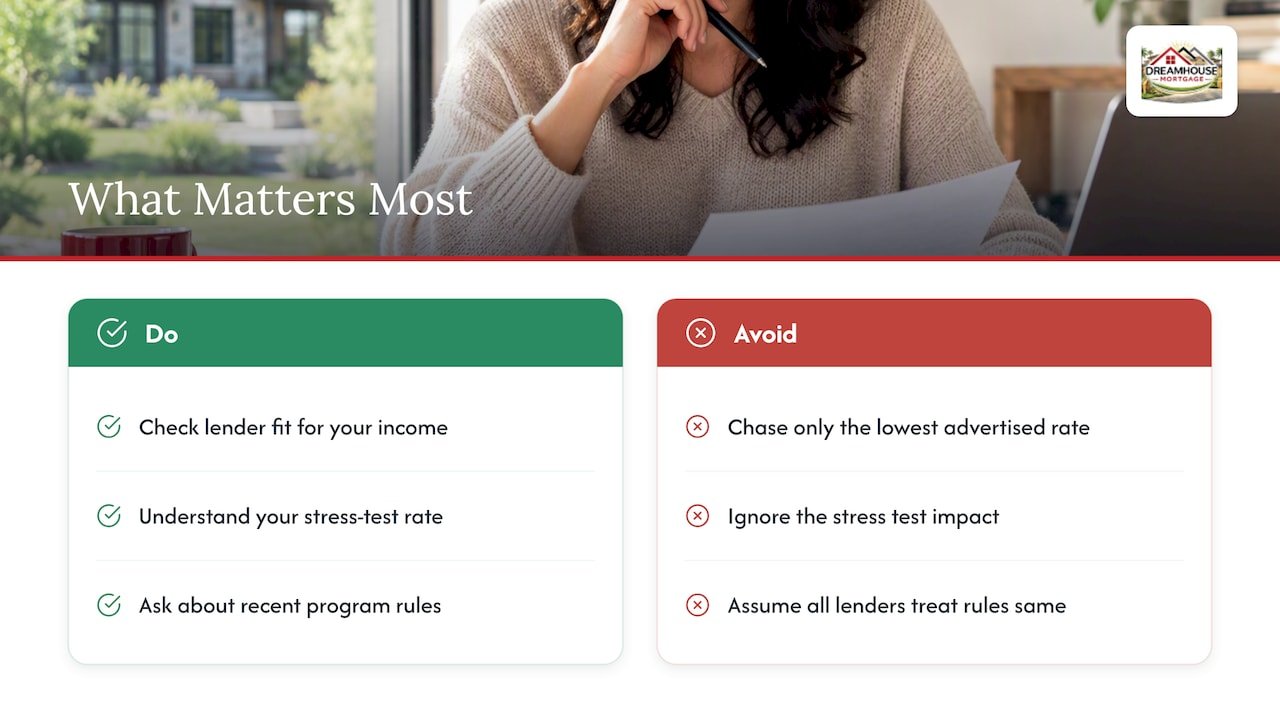
The stress test is the detail most first-time buyers underestimate. Qualifying at the federally mandated higher rate significantly impacts your maximum purchase price more than most rate shopping ever will, so understanding that rule before you fall in love with a listing matters more than picking a provider.
Recency matters too. With 30-year insured amortizations now available to more buyers and new first-time buyer savings tools in play, a provider who applies these rules correctly can change what you qualify for. Prioritize a provider who can explain your stress-test number and your program eligibility in plain terms before you compare a single rate.
— Guriqbal Chahal, MBA, PMP
Start your mortgage conversation with DreamHouse Mortgage
This brokerage can be a practical, direct option for first-time buyers and homeowners in the Alberta area who want one person handling lender comparison, paperwork, and mortgage qualification. Rather than juggling a bank’s limited products or starting from scratch with an online form, you get a local broker who already knows the Alberta lender landscape.
- Contact the mortgage broker directly to discuss your situation and options.
- Check reviews and confirm details through the Google Business Profile.
- Start online through the mortgage broker consultation page or explore first-time buyer mortgage options directly.
A first call typically covers your income type, timeline, and down payment source, enough for a clear next step without any obligation.
Sources
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What makes DreamHouse Mortgage a good alternative to a single broker’s site?
DreamHouse Mortgage gives you access to banks, credit unions, monoline lenders, and private lenders through one point of contact, rather than a single lender’s product list. Guriqbal Chahal, MBA, PMP, serves as Broker of Record and works directly with first-time buyers across Calgary, Airdrie, and Cochrane.
How does the mortgage stress test affect my choice of provider?
Federally regulated lenders must qualify you at the higher of 5.25% or your negotiated rate plus 2%, a rule that shapes your maximum purchase price more than small rate differences between providers, as explained on Canada.ca. Credit unions and some non-federally regulated lenders may apply different criteria, so ask directly how each provider handles it.
Are bank advisors or brokers better for first-time buyers?
Neither is universally better: a bank advisor offers one lender’s products with simple underwriting if you already bank there, while a broker compares multiple lenders and can place self-employed or nonstandard income with a better-fitting lender. The right choice depends on how straightforward your income and credit profile are.
What recent program changes should first-time buyers know about?
As of the federal reforms taking effect in late 2024, first-time buyers can use the Tax-Free First Home Savings Account and a higher Home Buyers’ Plan withdrawal limit, along with wider access to 30-year insured amortizations. A provider familiar with these changes can apply them directly to your qualification.
How fast can I get pre-approved through DreamHouse Mortgage?
Pre-approval timelines typically run a few days once your income, credit, and down payment documents are submitted. Call 403-966-6072 to confirm your specific timeline with Guriqbal Chahal, MBA, PMP, Mortgage Broker.