It works best as a short-term bridge for closing costs or renovations, not a long-term savings strategy. Before signing anything, get a side-by-side all-in cost comparison from a Calgary-based broker like Dreamhouse Mortgage.
TL;DR:
- Most cash back mortgage offers have higher interest premiums than the value of cash received over a five-year term, often making them more expensive in the long run.
- Clarifying the clawback formula, rate premium, and how offers change with down payment adjustments is crucial before deciding on a cash back mortgage.
- Using a broker to compare multiple lenders’ all-in costs helps avoid overpaying by understanding the true expense relative to standard mortgage options.
- Cash back benefits are best for covering short-term costs like closing fees or renovations and are not suitable for long-term savings or frequent refinancing plans.
- Local Alberta expertise ensures accurate comparisons and tailored advice, reducing the risk of costly mistakes caused by misinterpreting offers or lender fine print.
Table of Contents
- How Does a Cash Back Mortgage Work in Canada?
- How Do You Evaluate a Cash Back Offer Properly?
- What Does a Cash Back Mortgage Actually Cost You?
- Do You Qualify, and How Does It Affect Approval?
- Why Local Alberta Expertise Matters for This Decision
- What Calgary Buyers Get Wrong About Cash Back Mortgages
- Get Your Free Cash Back vs. Standard Mortgage Comparison
- Sources
- FAQ
How Does a Cash Back Mortgage Work in Canada?
You will run into two broad offer types when you shop this market: percentage-based cash back from the major banks, and fixed-dollar promotional credits that rotate in and out depending on the season. Both hand you money at or shortly after closing in exchange for accepting a rate premium above what you would pay on a standard mortgage, and that premium applies to your entire loan balance, not just the cash portion, according to the Financial Consumer Agency of Canada.
A mortgage brokerage can pull comparable offers from multiple lenders at once and run the all-in math for your specific numbers, rather than pitching you a single product. The bank-branded options below are widely available across Alberta, and each has its own structure.
A few things worth flagging before you shortlist anything:
- Promotional fixed-dollar offers change often, and a cap that applies this quarter may not apply next quarter, so confirm the current terms directly rather than relying on last year’s numbers.
- Lender cash back mortgages are typically offered through banks, credit unions, and brokers, and a broker can locate offers and calculate your all-in cost across several lenders in one pass.
- Availability often splits between new purchases and mortgage switches, so ask specifically whether the offer you are looking at applies to your scenario.
How Do You Evaluate a Cash Back Offer Properly?
Comparing cash back offers on the sticker amount alone is how buyers end up overpaying. The number that actually matters is your all-in cost: total interest paid over the term, minus the cash you received, compared against the same math on a standard mortgage at the lower rate. Run this using current Canadian mortgage rates for both scenarios before you decide anything.
- Get the exact rate premium in writing and confirm it applies for the full term, not just an introductory period.
- Ask for the precise clawback formula: how much you owe back, and on what schedule, if you break, refinance, or sell before the term ends.
- Confirm whether the premium and cap change if you increase your down payment or shorten your amortization.
- Ask whether the lender’s cash back tier sits on a rate grid, since larger cash back percentages are often paired with progressively higher rates rather than a flat add-on.
- Compare the offer against a standard mortgage quote from the same lender, not just against other cash back products.
Good uses for the cash: closing costs, legal fees, land transfer tax, or a defined renovation budget. Poor uses: treating it as free money when you plan to break the mortgage within a couple of years, since clawback repayment can erase most or all of the benefit.
Pro Tip: Ask your lender or broker to show you the lender’s published rate grid for every cash back tier side by side. If they can’t produce it, that is a signal to get a second opinion before you sign.
What Does a Cash Back Mortgage Actually Cost You?
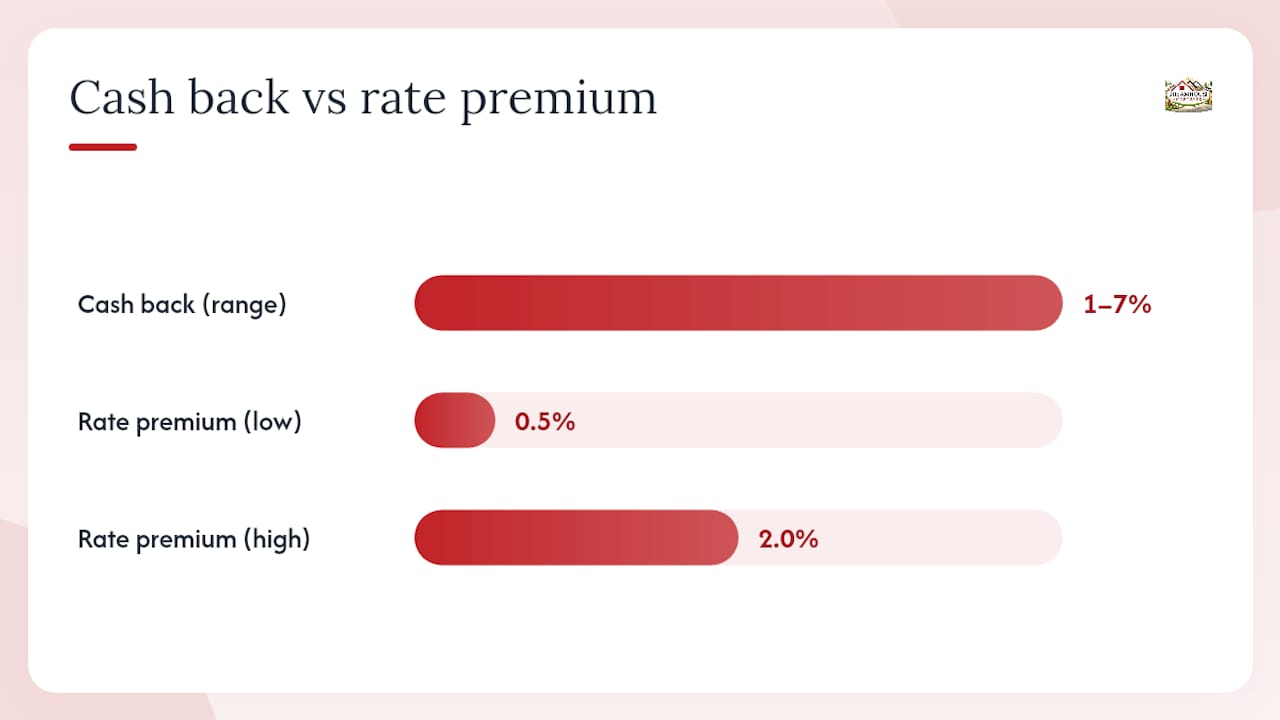
The typical cash back range runs 1% to 7% of your mortgage principal, and it comes paired with a rate premium of roughly 0.5% to 2.0% above the standard rate. That premium sits on your full loan balance for the term, which is why the math rarely favors the cash back option over five years.
Run the exact figures for your purchase price before assuming the cash back wins.
| Scenario | Cash received | Rate premium | Extra interest impact |
|---|---|---|---|
| Standard mortgage | $0 | None | Baseline |
| Cash back mortgage | Up to 7% of principal | 0.5%–2.0% on full balance | Often exceeds the cash received over a 5-year term |
The good news on the tax side: cash back received on a personal-use property is generally not taxable income, so whatever you receive is yours to use without a tax hit.
Do You Qualify, and How Does It Affect Approval?
Lenders assess cash back applicants the same way they assess any mortgage applicant: credit score, debt-service ratios, income documentation, and down payment source. The wrinkle is that a higher locked-in rate can affect your insured mortgage stress test math and your overall borrowing power, since CMHC guidelines apply the qualifying rate to whatever rate you accept.
- Self-employed borrowers typically need additional income documentation and may see stricter debt-service scrutiny with a higher-rate product.
- Newcomers to Canada often qualify through alternative credit history programs, which a broker can help structure alongside a cash back or standard option.
- Confirm your mortgage affordability numbers before assuming a cash back offer changes what you can borrow.
Why Local Alberta Expertise Matters for This Decision
This brokerage is led by an experienced broker who works with banks, credit unions, monoline lenders, and private lenders across Alberta to source and compare cash back options against standard mortgages. That access matters because no single bank branch will show you a competitor’s rate grid, and the clawback fine print differs from lender to lender.
Here is what a consultation with Dreamhouse Mortgage typically covers:
- Pulling comparable cash back and standard offers from multiple lenders for your specific purchase price and down payment
- Modeling the all-in cost of each option over your expected term, including clawback exposure
- Handling pre-approval, document collection, and lender selection so you are not managing five separate applications
- Explaining every clawback and rate-grid detail in plain language before you commit to anything
The brokerage serves buyers across Calgary, Airdrie, Cochrane, Chestermere, Okotoks, Edmonton, and surrounding Alberta communities. If you are house hunting in any of these areas, a local conversation before you apply can save you from locking into the wrong structure.
What Calgary Buyers Get Wrong About Cash Back Mortgages
The conventional advice treats cash back mortgages as either a trap to avoid entirely or free money to grab without thinking. Neither framing holds up once you actually run the numbers. A cash back mortgage is a financing tool with a specific job: bridging a short-term cash gap at closing. It is not a discount, and it is not a scam. It is a trade-off that needs to be priced against your actual plans for the property.
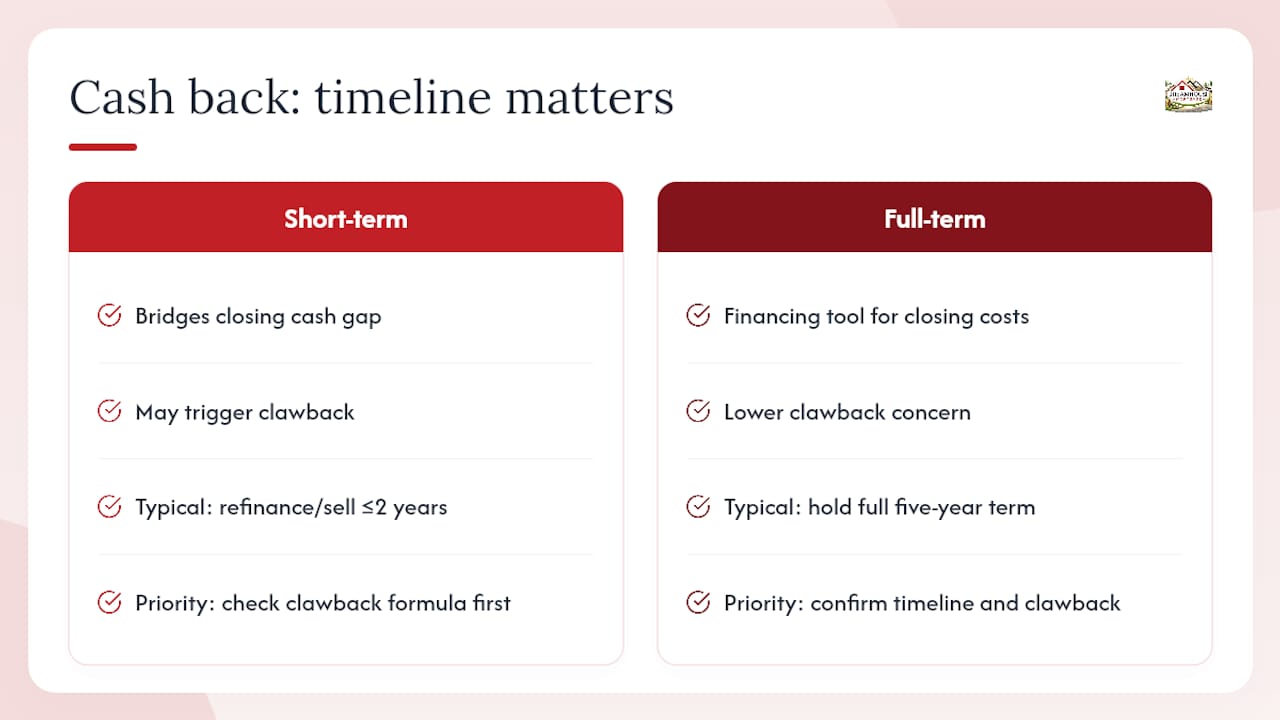
Where the standard advice falls short is treating every buyer’s timeline the same way. A buyer who plans to hold their mortgage for the full five-year term and needs cash for closing costs faces a very different calculation than a buyer who expects to refinance or sell within two years and could trigger a clawback. Most generic guides skip that distinction entirely.
What you should prioritize first is not the cash back percentage. It is the clawback formula and your realistic timeline in the property. Get those two answers before you look at a single rate. For most Calgary buyers, running the all-in cost comparison with a local broker before applying anywhere prevents the single most common and expensive mistake in this category: choosing the bigger check without pricing what it actually costs.
— Guriqbal Chahal, MBA, PMP
Get Your Free Cash Back vs. Standard Mortgage Comparison
Choosing between a cash back mortgage and a standard mortgage without running the full comparison is how buyers end up paying more in interest than the cash back was ever worth. This brokerage gives Calgary and area buyers access to banks, credit unions, monoline lenders, and private lenders all compared side by side, with the all-in cost math done for your actual numbers before you sign anything.
Call Guriqbal Chahal, MBA, PMP, Mortgage Broker, at 403-966-6072, or visit the mortgage pre-approval page to start your consultation. You can also find Dreamhouse Mortgage on its Google Business Profile. Before you call, have your purchase price, planned down payment, employment details, and income information ready so the comparison can be built around your real numbers from the first conversation. Whether you’re a first-time buyer in Airdrie or comparing a switch offer in Cochrane, get the full picture on Alberta financing before you commit to a rate.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Choosing a mortgage | Financial Consumer Agency of Canada
- How a Cash Back Mortgage Works – NerdWallet Canada
- Residential mortgage industry report | CMHC
FAQ
Is a Cash Back Mortgage a Good Idea?
It depends on your timeline. A cash back mortgage can make sense if you need money at closing and plan to keep the mortgage for the full term. However, the higher rate typically costs more in total interest than the cash back amount over a standard five-year term.
Which Bank Offers a Fixed-Dollar Cash Back Promotion?
TD, CIBC, and BMO have each run fixed-dollar promotional cash back offers on eligible purchases and switches, though the exact amount and eligibility change frequently, so confirm current terms directly with the lender or a broker.
Does CIBC Offer a Percentage-Based Cash Back Mortgage?
CIBC has historically focused on time-limited, fixed-dollar promotional cash back offers rather than a standing percentage-based product; current terms vary, so verify directly with CIBC or a mortgage broker.
How Much Income Do You Need to Qualify for a $500,000 Mortgage?
Required income depends on your down payment, debt load, credit score, interest rate, and the qualifying stress test rate applied under CMHC guidelines, so figures vary by buyer. A Calgary pre-approval consultation gives you an exact number based on your situation.
Can a Broker Get You a Better Cash Back Deal Than a Bank Directly?
A broker can compare cash back and standard offers across multiple lenders at once and calculate the all-in cost for your specific scenario, which a single bank branch typically cannot do since it only offers its own products.