A mortgage pre-approval is a conditional estimate of how much you may borrow based on your finances; final approval is granted only after the lender, and the insurer if applicable, reviews the property and your updated documentation. Pre-approval strengthens an offer, but it is not a binding mortgage commitment. Final approval depends on the specific home you want to buy, not just your income and credit.
TL;DR:
- Final approval requires an appraisal, a clean title search, updated income and credit documents, and insurer sign off when your down payment is below 20%.
- Debt, job changes, credit declines, or a low appraisal can reduce approval; qualification uses the higher of 5.25% or your contract rate plus 2%.
- Do not remove your financing condition until the lender confirms firm approval in writing; a verbal assurance does not protect you if financing later fails.
- After an accepted offer, appraisal and underwriting usually take days to weeks; rural or unusual properties and insurer requests can extend the timeline.
Table of Contents
- What Mortgage Pre-Approval Means in Canada
- What Final Mortgage Approval Involves
- At-a-Glance Differences: Pre-Approval vs Approval
- What Can Change Between Pre-Approval and Final Approval
- Timeline: How Long Pre-Approval Lasts and How Long Final Approval Takes
- Checklist: Documents to Move From Pre-Approval to Approval
- Broker Perspective: Supporting Approval for Calgary Buyers
- When Is Approval Actually Confirmed?
- How Reliable Is a Pre-Approval, Really?
- Costs and Fees: Pre-Approval vs Full Approval
- Strategy by Buyer Type: First-Time, Self-Employed, and Newcomer Buyers
- Our Take: Treat Pre-Approval as a Compass, Not a Contract
- Get a Local Mortgage Review Before You Make an Offer
- FAQ
- Sources
What Mortgage Pre-Approval Means in Canada
Pre-approval is the financial check that happens before you start shopping seriously for a home. A lender reviews your income, credit history, existing debt, and down payment source, then tells you roughly how much you can borrow and at what rate. What pre-approval does not do is look at a specific property, because at this stage you likely have not found one yet. According to Canada, a pre-approval is not a guarantee of a loan: it is an estimate, and it leaves out the appraisal that final underwriting requires.
Pre-approval letters typically include conditional language, meaning the number you receive depends on your circumstances staying the same.
- The lender checks income, credit score, debt ratios, and down payment proof.
- No property is assessed at this stage, so the appraisal step comes later.
- The letter usually states a maximum loan amount tied to unchanged employment and credit.
- Sellers and their agents often view a pre-approval letter as a sign you can follow through on an offer.
What Final Mortgage Approval Involves
This is the stage where the actual property enters the picture, along with a fresh look at your paperwork.
- A professional appraisal confirms the home’s value supports the purchase price.
- A title search verifies the property is free of claims that could affect the lender’s security.
- If your down payment is below 20%, mortgage loan insurance is typically required, and the lender coordinates that review.
- Income and employment are verified again, often with updated pay stubs or an employer letter.
For insured mortgages, the insurer’s sign-off is a separate step that the pre-approval never touched, which is one reason the two stages can produce different outcomes.
At-a-Glance Differences: Pre-Approval vs Approval
Seeing both stages side by side makes it easier to know what has actually been confirmed at each point in your home search.
- Credit and income check: confirmed at pre-approval, then reverified at final approval with updated documents.
- Property appraisal: skipped entirely at pre-approval, required before final approval is issued.
- Title search: not part of pre-approval, completed during final underwriting.
- Insurer review: absent from pre-approval, required for insured mortgages (under 20% down) before final approval.
- Conditional language: pre-approval letters list conditions such as unchanged employment and credit; final approval removes those conditions once verified.
- Confidence level: a pre-approval lets you shop with a realistic budget, but you should stay cautious about overcommitting until conditions are formally removed.
The phrase “conditions removed” is the real milestone. Once a lender confirms the property, your documents, and the insurer’s approval, the conditional language disappears and the mortgage becomes a firm commitment.
What Can Change Between Pre-Approval and Final Approval
A pre-approval reflects a snapshot of your finances on the day it was issued. Several things can shift before closing, and any of them can affect the final outcome.
- A change in employment, a drop in income, or a new job probation period can affect your qualification.
- New debt, such as a car loan or increased credit card balance, raises your debt ratios.
- A lower credit score from missed payments or new inquiries can change the rate or terms offered.
- An appraisal that comes in below the purchase price can reduce how much the lender will fund.
- The mortgage insurer may impose new conditions or decline a file the lender was otherwise ready to approve.
Pro Tip: Avoid opening new credit accounts, financing furniture, or switching jobs between your pre-approval and your closing date.
The mortgage stress test also plays a role here. Federally regulated lenders qualify you using the higher of 5.25% or your contract rate plus 2%, so a rate movement between pre-approval and offer can change how much you actually qualify for at final approval.
Timeline: How Long Pre-Approval Lasts and How Long Final Approval Takes
Pre-approvals are not open-ended. Lenders typically hold a pre-approval rate for a limited period, after which you will need to requalify or request an extension if you have not yet found a home.
- Ask your broker to confirm the exact expiry date in writing when you receive your pre-approval letter.
- Once you have an accepted offer, appraisal and underwriting typically move within days to a few weeks, depending on lender workload and property type.
- Insurer review for insured mortgages can add time if additional documentation is requested.
- Coordinate your subject removal date with your broker so you are not racing the clock on financing conditions.
Rural properties, unique homes, or files needing extra income verification tend to move slower, so building in a buffer before your subject removal deadline is worth the effort.
Checklist: Documents to Move From Pre-Approval to Approval
Once your offer is accepted, speed matters. Having these items ready keeps your file moving instead of sitting in a lender queue.
- Proof of income: recent pay stubs and T4 slips, or two years of filings for self-employed applicants.
- Notice of Assessment from the Canada Revenue Agency for the most recent tax year.
- Recent bank statements showing the source and seasoning of your down payment funds.
- A signed copy of the purchase contract with all conditions and dates clearly stated.
- Contact information for your employer, in case the lender requests income verification directly.
Tell your broker the moment your offer is accepted so appraisal scheduling can start right away. For a full breakdown of what Calgary and Alberta lenders ask for, our mortgage pre-approval documents checklist covers each item in more detail.
Broker Perspective: Supporting Approval for Calgary Buyers
Guriqbal Chahal, MBA, PMP, is Broker of Record at a mortgage brokerage based in Calgary, serving buyers across Airdrie, Cochrane, Chestermere, and surrounding Alberta communities. We coordinate documentation, match each file to lenders whose underwriting approach fits the borrower’s specific situation, and walk clients through insurer requirements before they become a surprise at the final stage.
For Calgary-area buyers, local appraisal timing and lender flexibility on certain documentation can differ by neighborhood and property type, which is where a broker’s day-to-day market experience matters. If you want a local review of your file before you make an offer, our mortgage pre-approval process guide walks through what Alberta lenders expect.
When Is Approval Actually Confirmed?
Approval is confirmed when every condition attached to your financing has been formally removed in writing by the lender, not when you simply receive a congratulatory call. This moment, often called “firm approval” or a firm mortgage commitment, happens after the appraisal supports the purchase price, the title search comes back clean, your income and credit are reverified, and the insurer, if one is involved, has signed off on the file.
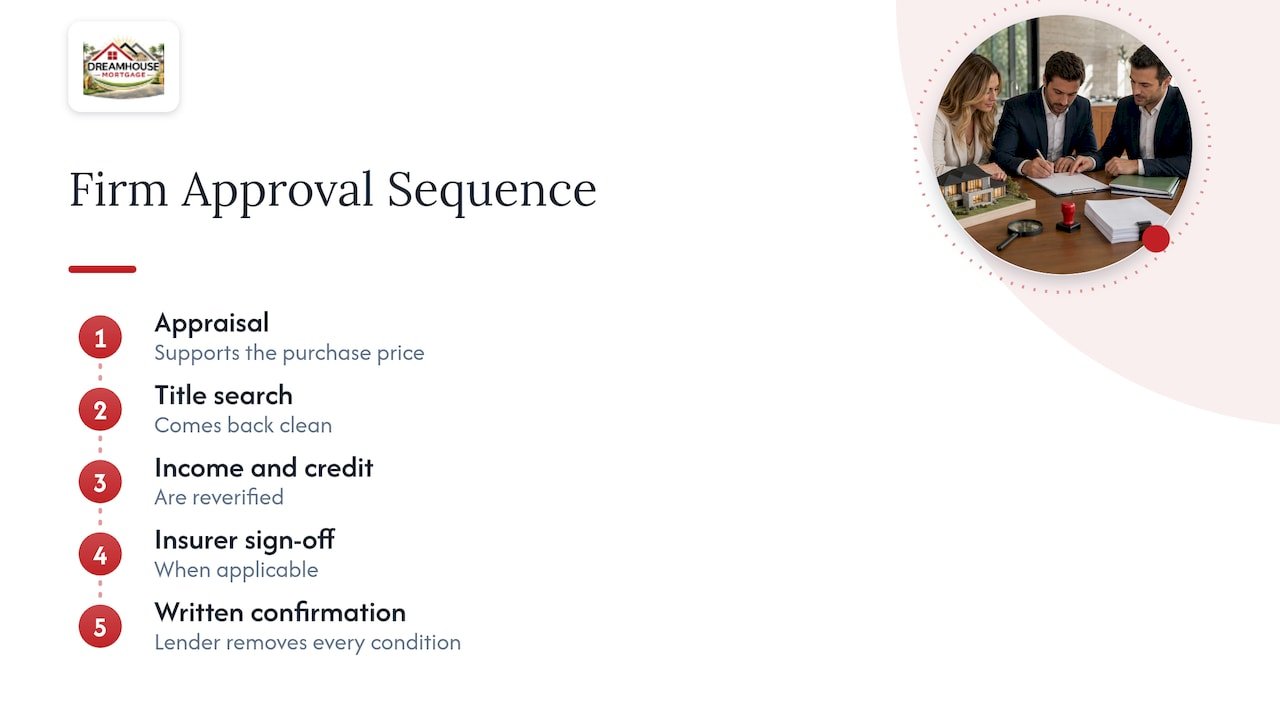
Until that point, your financing is still conditional, even if everyone involved expects it to go smoothly. This distinction matters most around your subject removal date in the purchase contract. If you remove your financing condition before the lender has issued firm approval, you have given up your legal ability to walk away from the deal without financial consequence if financing later falls through.
Sellers benefit from this structure too. A firm offer, meaning one where conditions have been removed, gives a seller confidence the deal will close, which is part of why competitive markets sometimes see buyers pressured to remove conditions early. A careful broker will tell you not to remove a financing condition until the lender has actually confirmed approval in writing, not just verbally. That written confirmation, sometimes called a commitment letter, is the document that protects both sides of the transaction.
How Reliable Is a Pre-Approval, Really?
A pre-approval is a useful planning tool, but it is not a promise. According to Canada.ca, pre-approval letters outline a maximum loan amount that depends on your circumstances staying consistent and on the property passing final assessment. Neither of those things is guaranteed at the time the letter is issued.
The most common reasons a final approval gets reduced or refused trace back to one of three sources. First, the borrower’s situation changes: a new debt, a lower credit score, or a change in employment can shift the numbers the lender originally relied on. Second, the property itself creates a problem: an appraisal below the agreed purchase price, title issues, or a condition report that raises concerns for the lender or insurer. Third, documentation does not match what was assumed at pre-approval, which happens more often with self-employed income or irregular deposits that need a clearer paper trail.
None of this means pre-approval is not worth getting. It tells you a realistic price range, helps you avoid wasting time on homes outside your budget, and gives sellers confidence that you are a serious buyer. Just treat it as a strong starting point rather than a finish line, and keep your financial picture as stable as possible until the lender issues firm approval.
Costs and Fees: Pre-Approval vs Full Approval
Getting pre-approved generally does not cost you anything out of pocket when working with a broker, since brokerage compensation comes from the lender once a mortgage funds, not from the borrower at the pre-approval stage. The main cost consideration during pre-approval is a credit check, which can cause a small, temporary dip in your credit score.
Costs tend to appear at the final approval stage instead. An appraisal fee may apply, particularly if the lender requires an independent appraisal rather than using an automated valuation. If your down payment is under 20%, mortgage loan insurance premiums are added to your mortgage, and the lender coordinates this on your behalf as part of final underwriting. Legal fees for the title search and closing, home inspection costs if you choose to have one, and any lender-specific administration fees also show up around this stage rather than at pre-approval.
Because most of the real costs land during final approval and closing, it is worth budgeting for them early rather than assuming pre-approval covers the full financial picture. A broker can give you a realistic estimate of these closing costs based on your specific lender and property type before you remove conditions.
Strategy by Buyer Type: First-Time, Self-Employed, and Newcomer Buyers
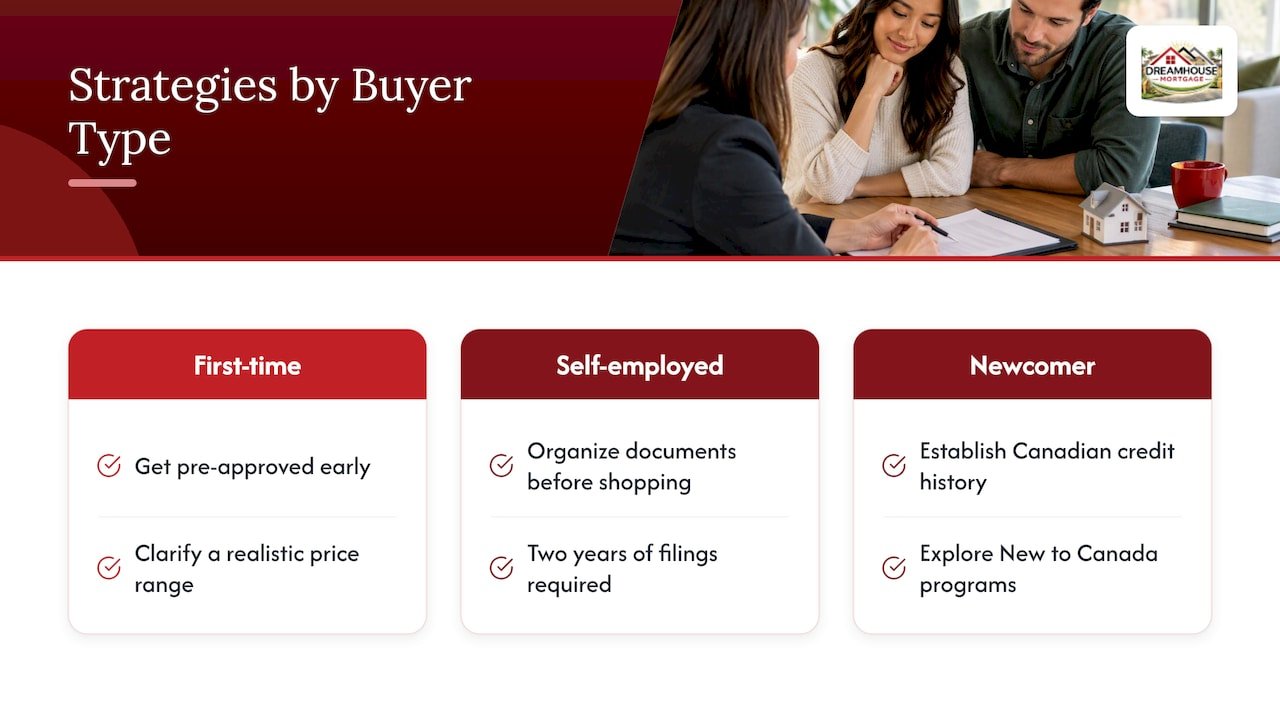
How you treat pre-approval and final approval should shift depending on your situation. First-time buyers in Calgary and Alberta often benefit most from getting pre-approved early, since it clarifies a realistic price range and avoids the disappointment of falling for a home outside their budget. Our first-time home buyer resources walk through the specific programs and down payment options available to new buyers in the province.
Self-employed buyers face more scrutiny at the final approval stage, since lenders need two years of filings and a Notice of Assessment to verify income that does not come with a standard pay stub. Pre-approval for a self-employed applicant is often a rougher estimate than for a salaried buyer, so it pays to have your documentation organized well before you start shopping.
Newcomers to Canada typically need to establish a credit history or work with lenders offering New to Canada mortgage programs, since limited Canadian credit history can affect both the pre-approval estimate and the final underwriting review. In each case, the gap between pre-approval and final approval tends to be wider for buyers with non-standard income or limited credit history, which makes early, honest conversations with a broker more valuable than the pre-approval number itself.
Our Take: Treat Pre-Approval as a Compass, Not a Contract
The biggest misunderstanding we see among Calgary buyers is treating a pre-approval letter as proof a mortgage is locked in. It is not, and conventional advice that stops at “get pre-approved and start shopping” leaves out the part that actually determines whether a deal closes: the appraisal, the insurer, and the paper trail behind your income.
What matters more than the pre-approval number itself is how stable your financial picture stays afterward. A buyer with a modest pre-approval and a clean, unchanged file in final underwriting will often close faster and with fewer surprises than a buyer with a larger pre-approval who changes jobs or opens new credit mid-process.
Our honest recommendation: use pre-approval to set your price range and shop with discipline, but hold off on removing financing conditions until your lender has issued firm, written approval. That single habit prevents more failed deals than any amount of extra pre-approval shopping around for a slightly better rate.
— Guriqbal Chahal, MBA, PMP
Get a Local Mortgage Review Before You Make an Offer
We help Calgary, Airdrie, Cochrane, Chestermere, and Okotoks buyers move from pre-approval to a firm mortgage commitment without the guessing. We coordinate documents, match your file to lenders whose underwriting approach fits your situation, and manage insurer requirements to help keep your deal on track.
- Pre-approval guidance tailored to your income type, including self-employed and newcomer files.
- Document coordination so your final approval moves quickly once your offer is accepted.
- First-time buyer support across Calgary and the surrounding Alberta communities.
Call Guriqbal Chahal, MBA, PMP, Mortgage Broker at DreamHouse Mortgage, at 403-966-6072, or visit our mortgage pre-approval page to start your file today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What’s the difference between approval and pre-approval?
Pre-approval is an estimate based on your income, credit, and down payment, with no property review involved. Final approval happens after the lender and, if applicable, the insurer review the specific property, title, and updated documents, and it results in a firm written commitment.
How long does a mortgage approval take in Canada?
Once you have an accepted offer, appraisal and underwriting typically move within days to a few weeks, though insured mortgages or files needing extra documentation can take longer. Coordinating closely with your broker helps keep the timeline aligned with your subject removal date.
What is a mortgage in principle?
In Canada, this term is used loosely and generally refers to what lenders call a pre-approval: an estimate of how much you can borrow based on your finances, issued before you have a specific property in mind. It is not a guarantee of final approval, since the property and updated documents still need to be reviewed.
How rare is a 900 credit score in Canada?
There is no published Canadian data specifying how common a specific credit score is, and credit score ranges and reporting can vary by bureau. What matters for mortgage qualification is less about reaching a perfect score and more about meeting the debt ratios and stress test requirements lenders apply, such as the GDS and TDS benchmarks used in FCAC’s mortgage qualifier tool.
Sources
Recommended
- Mortgage Approval Time Calgary: How Long It Really Takes & How to Speed It Up
- 5–10 Day Window: Appraisal vs Inspection Mistakes Calgary Buyers Make
- Conditional Mortgage Approval Alberta Explained: The Critical Difference Between Conditional and Unconditional Approval
- Mortgage Pre-Approval Process Explained for Alberta Buyers