Yes, you can get mortgage financing for a manufactured home in Alberta. The decisive factor is whether the home is permanently affixed to land you own. If it is, a traditional mortgage is usually available; if the home sits on a rented site, you will likely need chattel or specialized financing, and the federal stress test and Canada’s down payment rules still apply either way.
TL;DR:
- Lenders classify homes by foundation, construction standards, and legal status, so confirm whether the unit is real property or personal property before applying.
- Federally regulated lenders qualify borrowers at the higher of their contract rate plus 2% or 5.25%, and require income, credit, and title or lease documents.
- Buyers need 5% down on the first $500,000 and 10% on the portion up to $1.5 million; down payments below 20% require mortgage insurance.
- CMHC Prefab Plus insures prefabricated and modular homes up to $1.5 million and supports up to four progress draws; Home Start extends amortization to 30 years.
- Site renters should check lease limits on moving or modifications, tax responsibility, fee increase notice, and maintenance duties under Alberta’s Mobile Home Sites Tenancies Act.
Table of Contents
- Manufactured, modular, and RTM homes: how lenders classify them
- Land ownership vs. site lease: how MHSTA affects your financing
- Mortgage eligibility: stress test, income, and documents you’ll need
- Down payment rules, insurance, and CMHC Prefab Plus basics
- Choosing between banks, credit unions, and chattel lenders
- Your pre-approval checklist before you shop for a home
- Why local expertise matters for manufactured home buyers
- Get help financing your manufactured home in Calgary
- FAQ
- Sources
Manufactured, modular, and RTM homes: how lenders classify them
Before you apply for financing, we need to know exactly what kind of home you are buying, because lenders treat each category differently.
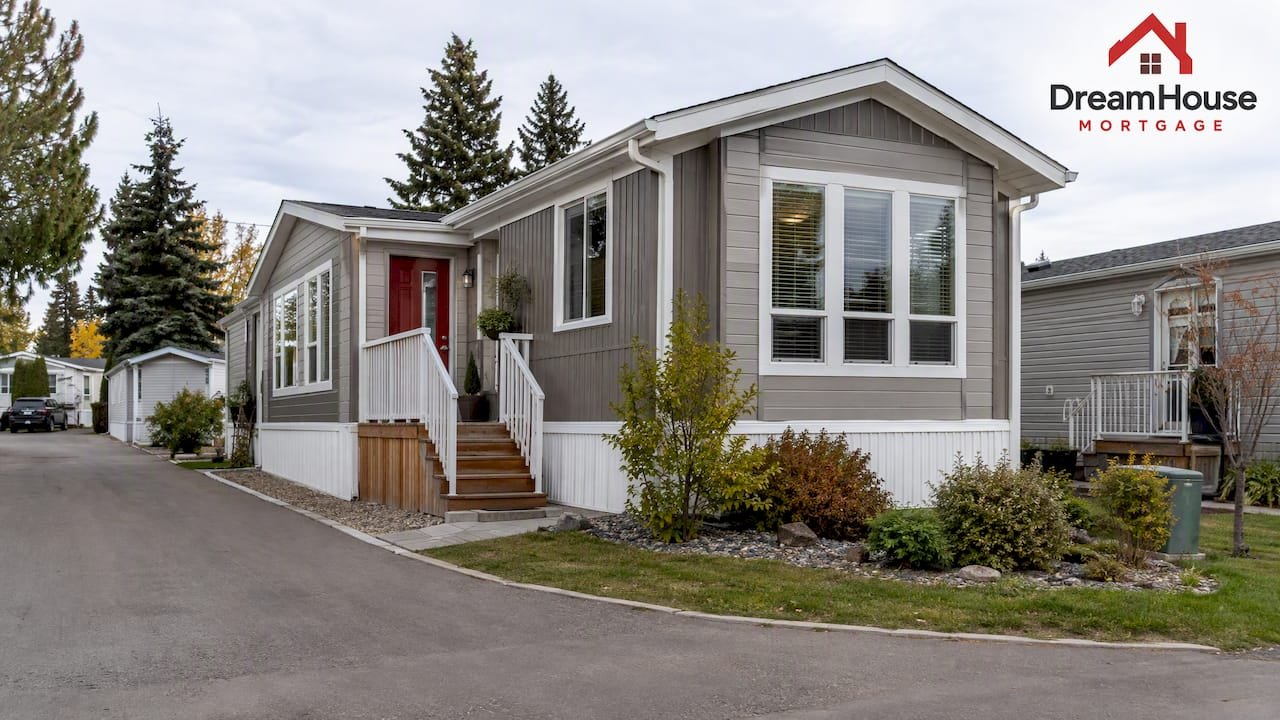
A manufactured or mobile home is typically built in a factory, placed on a chassis, and designed so it can be moved. A modular home, sometimes called a ready-to-move (RTM) home, is also factory-built, but its sections are transported to the site and permanently assembled on a foundation, much like a conventionally built house. That distinction matters enormously for financing, since lenders generally reserve traditional land-secured mortgages for homes that are permanently fixed to owned land.
Lenders commonly check:
- Whether the home sits on a permanent foundation
- Whether it meets the applicable requirements for its construction type
- Whether the unit is legally classified as real property or personal property (chattel)
Getting this classification right early saves time, since it determines which lenders and products are even on the table.
Land ownership vs. site lease: how MHSTA affects your financing
The single biggest factor in qualifying for a manufactured home mortgage in Alberta is whether you own the land underneath your home.
If you own the lot and the home is permanently affixed to a foundation, lenders generally treat the property as real estate, opening the door to a conventional mortgage with standard amortization and rates. If you are renting a pad in a mobile home park, most lenders will only offer chattel financing, since the home itself, not the land, secures the loan.
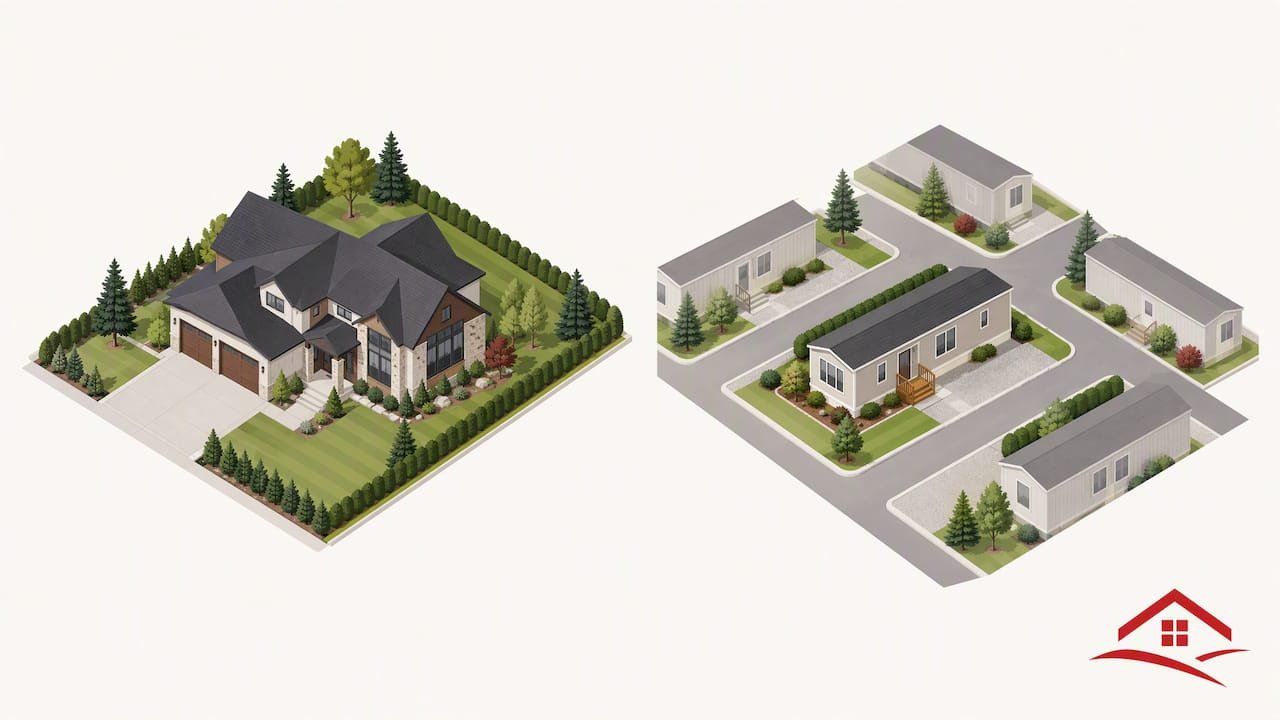
Renting a site also means your tenancy falls under Alberta’s Mobile Home Sites Tenancies Act, which sets out rules on security deposits, notice for fee increases, landlord disclosure, and maintenance responsibilities.
Before applying, confirm:
- Who is responsible for property taxes under your ownership or lease arrangement
- Whether any lease clauses restrict moving or modifying the home
- The full terms of your site lease, including fee-increase notice periods
Mortgage eligibility: stress test, income, and documents you’ll need
Every federally regulated lender in Canada applies the same qualifying test, regardless of whether the home is a bungalow in Airdrie or a modular home outside Cochrane. You must prove you can afford payments at the higher of your contract rate plus 2% or 5.25%, a rule set by Canada’s banking regulator that protects both lenders and borrowers from rate shocks at renewal.
To move through underwriting smoothly, expect to provide:
- Government-issued identification
- Recent pay stubs, T4s, or Notices of Assessment
- A current credit report and score
- Proof of land title or a copy of your site lease
- Permits or foundation documentation if the home is newly placed or modular
Self-employed buyers and newcomers to Canada may need to discuss their income and credit documentation with a lender or broker. A broker can help identify lenders whose requirements fit your circumstances. Our mortgage qualification guide walks through documentation requirements in more detail.
Down payment rules, insurance, and CMHC Prefab Plus basics
Canada’s down payment bands apply to manufactured and modular homes the same way they apply to any other home purchase. You need a minimum of 5% of the purchase price up to $500,000, and for homes priced between $500,000 and $1.5 million, 5% on the first $500,000 plus 10% on the portion above that. Any down payment under 20% requires mortgage loan insurance, which affects your monthly payment and how the insurer underwrites your file.
CMHC’s Prefab Plus program insures prefabricated and modular homes for homeowner loans up to a maximum purchase price of $1,500,000, with maximum amortization of 25 years, extendable to 30 years through CMHC’s Home Start option. This matters for Alberta buyers because:
- Homes permanently affixed to owned land can qualify for traditional mortgage insurance through Prefab Plus
- Movable units typically fall outside this program and require chattel financing instead
- Prefab Plus supports up to four progress draws, which helps sequence land purchase, foundation work, and final home delivery
Our CMHC mortgage insurance breakdown covers how these premiums are calculated for Alberta buyers.
Choosing between banks, credit unions, and chattel lenders
The lender you work with depends almost entirely on how your home is classified.
- Banks and many credit unions finance homes on permanent foundations with owned land, offering standard rates and amortization comparable to any resale home
- Chattel loans secure the manufactured home itself rather than the land, and their terms vary by lender
- Alternative and private lenders, along with specialty programs, may be options for movable units or site-leased homes
Working with a broker means we can place your file with whichever lender type actually fits your situation, rather than you guessing which bank will say yes. That matters in Alberta, where manufactured home purchases in Calgary, Cochrane, and Airdrie may involve owned land or leased pad sites, which can affect the financing options available.
Your pre-approval checklist before you shop for a home
Getting organized before you apply saves weeks of back-and-forth with underwriters.
- Confirm land title or review your site-lease agreement in full
- Order a title search through Alberta’s land titles system to confirm ownership, caveats, and existing encumbrances
- Gather building permits or foundation documentation if the home is new or relocated
- Pull together income documents, credit report, and identification
- Confirm property insurance arrangements and municipal access or permitting requirements
- If renting a site, verify MHSTA responsibilities with your landlord before signing anything
Pro Tip: Talk to an Alberta mortgage broker before you make an offer. We can pre-check which lenders accept manufactured or modular home financing for your specific situation, which avoids wasted conditions and financing walk-throughs.
For a deeper walkthrough, see our mortgage pre-approval guide for Alberta buyers.
Why local expertise matters for manufactured home buyers
Manufactured and modular home financing in Alberta comes with more moving parts than a standard resale purchase: land status, site leases, CMHC program limits, and lender appetite all shift the outcome. We work with buyers across Calgary, Cochrane, Airdrie, and surrounding Rocky View County communities, matching manufactured home purchases to lenders who actually underwrite them. Getting a broker involved early, before you write an offer, is what keeps these files from stalling.
— Guriqbal Chahal, MBA, PMP
Get help financing your manufactured home in Calgary
We help Calgary-area buyers sort through land ownership questions, site-lease terms, CMHC program eligibility, and chattel financing options so you are not left guessing which lender will approve your file. Whether you are purchasing a modular home near Okotoks or a manufactured home on leased land outside Chestermere, we match you to a lender built for that exact situation.
Working with us means:
- One point of contact who coordinates land title checks, income documentation, and lender submissions on your behalf
- Access to banks, credit unions, monoline, alternative, and private lenders, so a rented-site home is not automatically a dead end
- A Mortgage Pre-Approval review tailored to manufactured and modular home purchases in Calgary, Cochrane, and Airdrie
Call Guriqbal Chahal, MBA, PMP, Mortgage Broker at DreamHouse Mortgage, at 403-966-6072, or visit our Google Business Profile to book a consultation and start your pre-approval today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can you get a mortgage for a mobile home in Alberta?
Yes, but the financing route depends on land ownership. If the home is permanently affixed to land you own, a traditional mortgage is usually possible; if it sits on a rented site under the Mobile Home Sites Tenancies Act, chattel or specialized financing is more common.
What are the new mortgage rules in Canada for 2026?
Federally regulated lenders still require all borrowers to qualify at the higher of their contract rate plus 2% or 5.25%. CMHC also expanded its Prefab Plus program in 2026 to insure more prefabricated and modular home purchases, supporting staged progress draws during construction.
What is the best way to finance a mobile home?
The strongest option is a traditional mortgage secured against owned land with a permanently affixed home, since this typically offers better rates and longer amortization than chattel financing. Working with a mortgage broker helps you identify whether your home qualifies for CMHC Prefab Plus or requires a chattel loan instead.
How much mortgage can I get with a $70,000 salary in Canada?
Your maximum mortgage amount depends on your down payment, debt obligations, credit history, and the stress test qualifying rate, not salary alone. A mortgage broker can calculate your specific affordability range using current lender guidelines and your full financial picture.
Sources
Recommended
- Calgary Buyers’ 5 Step Checklist to Secure an Alberta Land Mortgage
- The Ultimate Guide to Buying a Second Home in Alberta: The Truth About Second Home Mortgage Alberta Options
- Legal Basement Suite Mortgage Calgary: How Rental Income Is Calculated, Approved, or Rejected by Lenders
- Mortgage Terms Explained Alberta Mortgage Glossary: 60 Essential Terms Every Calgary Buyer Must Know (2026)