A mortgage pre-approval in Alberta is usually good for about 90 to 120 days, but there is no single provincial rule. The length is set by each lender, and the Financial Consumer Agency of Canada (FCAC) says lenders may let you lock in a rate for 60 to 130 days, depending on the lender. If you are shopping in Calgary, Airdrie or Cochrane, the number that matters is the one written in your own pre-approval letter, and the date your purchase must fund by.
This guide explains what “valid” really means, how the rate hold differs from the pre-approval itself, what can end a pre-approval early, and how to time your search so you are not left starting over.
TL;DR
- Most Canadian pre-approvals hold a rate for 60 to 130 days. Major lenders commonly sit at 120 days, and some at 130.
- The rate hold protects your rate. It does not guarantee final approval, which still depends on the property, your file and the lender’s underwriting.
- A job change, new debt or a drop in income can affect your approval even inside the validity window.
- If a pre-approval expires, you can usually update it with fresh documents and a new credit check, so start the renewal conversation before the deadline.
- Call Guriqbal Chahal, MBA, PMP, at 403-966-6072 to confirm your dates and plan your Calgary-area purchase around them.
Table of Contents
- How long is a pre-approval valid in Alberta?
- Pre-approval expiry versus rate-hold expiry
- A pre-approval is not a final approval
- What happens if your pre-approval expires
- Shopping around without hurting your credit
- Documents that keep your pre-approval on track
- Pre-approval and pre-qualification are not the same
- Choosing a hold length that fits your purchase
- Our perspective
- Plan your pre-approval with DreamHouse Mortgage
- FAQ
- Sources
How long is a pre-approval valid in Alberta?
There is no Alberta-specific limit. Mortgage lending in Canada is run by lenders under federal and provincial consumer rules, and the validity period is a product feature each lender chooses. In practice, you will see these ranges:
| Source | Stated hold period |
|---|---|
| FCAC (Government of Canada) | 60 to 130 days, depending on the lender |
| RBC Royal Bank | Up to 120 days from the application date |
| TD Canada Trust | 120 days, subject to all conditions being met |
| BMO | Terms locked in for 130 days |
| Rates.ca overview | Commonly 30, 45, 60, 90 or 120 days; Desjardins sometimes up to 180 days |
Two practical points follow from the table. First, the clock normally starts on the application or approval date, not on the day you begin house hunting. Second, a longer hold is not automatically better: what counts is whether the hold, the product and the rate suit the purchase you are making.
Pro Tip: Read the expiry date on your letter the day you receive it and put it in your calendar with a reminder 30 days earlier. Buyers in Calgary’s faster-moving price ranges often lose weeks to showings and offers before they realize the clock has been running.
Pre-approval expiry versus rate-hold expiry
These two dates are often treated as one, and that causes confusion. They are related but not identical.
- Pre-approval validity is the period during which the lender stands behind the assessment it made of your income, credit, debts and down payment. Your documents and credit report are reviewed as they were on that date.
- Rate hold is the period during which the lender promises not to charge you more than the quoted rate for the term you chose.
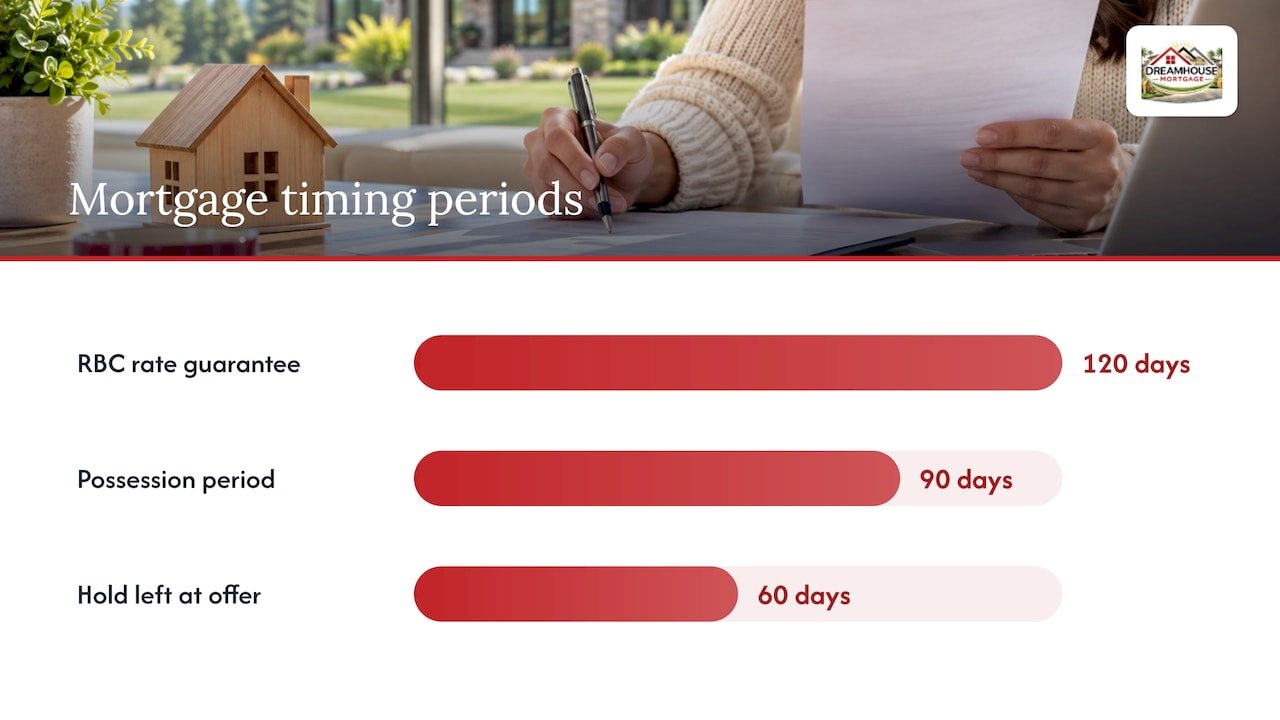
In most cases the two run together, so the letter shows a single date. The practical point is that the rate protection ends on whichever comes first: the expiry of the hold or the closing of your mortgage. RBC’s own wording makes this concrete: the rate guarantee lapses if the mortgage is not funded within the 120-day period. Funding, not just an accepted offer, is the milestone.
That detail matters for Alberta buyers purchasing new builds or resale homes with longer possession dates. If you have a 90-day possession on a home in Cochrane or Airdrie and your hold has 60 days left when you write the offer, the rate protection may end before you get the keys. We cover this timing question in more depth in our guide on why Calgary buyers need both a rate hold and a pre-approval.
What the rate hold does when rates move
A hold works in your favour if rates rise. If rates fall, some lenders will let you benefit: TD states that if the rate on your chosen term goes down, you can ask to have it adjusted to the lower current rate. Policies differ from lender to lender, so ask whether a lower rate can be applied before you sign anything. A mortgage broker can compare how different lenders treat this.
A pre-approval is not a final approval
Validity and certainty are two separate questions. FCAC states plainly that the pre-approval process does not guarantee your approval for a mortgage. Rates.ca makes the same point: a lender guarantees a rate during the hold, but it must still verify your credit history, documentation and other financial details.
What changes between pre-approval and final approval in Calgary?
- The property. The lender reviews the actual home, including its appraisal. An appraisal that comes in below the purchase price can change how much the lender will advance. We explain this in Preapproval vs Approval: Calgary Appraisals Can Change the Deal.
- The documents. Pay stubs, employment letters, bank statements and the source of your down payment are checked against what you reported.
- Your credit and debts. A new car loan, a larger credit card balance or a new line of credit can alter your debt servicing ratios.
- Your employment. A move from salaried to commission pay, or a change of employer during probation, can trigger fresh review.
RBC notes that significant changes to your financial situation, such as a new job, increased debt or shifts in income, could affect your approval even within the initial period. Its terms also say the borrower must maintain the credit status as at the time of application, and that the bank can decline credit up to and including the closing date if circumstances change. Treat that as standard good practice for any lender: keep your finances steady until the keys are in your hand.
Pro Tip: Between pre-approval and possession, avoid financing furniture, vehicles or appliances, and avoid moving money between accounts without a paper trail. Lenders look at where your down payment came from, and large unexplained deposits slow files down.
What happens if your pre-approval expires
It is not the end of the road, but it does mean extra work. RBC says that if your pre-approval expires before you find a home, you will need to reapply, which may involve updating your financial information and a new credit check. Its online terms add that if the commitment lapses, you must contact the bank to update your pre-approval. Other lenders follow a similar pattern, though exact requirements vary.
In practical terms, when you renew you should expect to:
- Provide current pay stubs and an updated employment letter.
- Supply recent bank or investment statements showing your down payment.
- Disclose any new debts or changes to existing ones.
- Accept the rate that applies on the renewal date, which may be higher or lower than your original quote.
That last point is the real cost of letting a hold lapse. Rates.ca warns that if a borrower does not close on time and rates have gone up, lenders will not extend the previously guaranteed rate past the deadline. It also notes that holds are often shorter for renewals and refinances, which matters if you are a homeowner in Calgary comparing a purchase to a refinance.
A simple timeline for Calgary buyers
Here is a sample plan for a first-time buyer using a 120-day hold. The numbers are an illustration, not a lender rule.
- Day 0: Pre-approval issued. Note the expiry date.
- Days 1 to 30: Set your budget, meet your realtor and start viewings in the communities that fit, such as Airdrie, Cochrane, Chestermere or Calgary neighbourhoods like Mahogany, Skyview Ranch or Seton.
- Days 30 to 80: Write offers. If an offer is accepted, send the purchase contract to your broker immediately.
- Day 80 onward: Complete conditions, appraisal and lender documents. Confirm that closing falls before the hold ends.
- Day 90: If you still have no accepted offer, ask for an update before the hold runs out rather than after.
The sooner the file moves from “pre-approved” to “submitted with an accepted offer”, the less the expiry date matters.
Shopping around without hurting your credit
Many buyers delay pre-approval because they worry about credit inquiries. ATB Financial, an Alberta-based lender, states that multiple mortgage inquiries within a 45-day period have the same credit score impact as one. That means comparing options in a compact window is sensible. A mortgage broker can arrange this so that your inquiries are grouped and you see several lenders’ terms side by side.
This is also one of the reasons the order of events matters. Start your pre-approval work in a focused stretch, choose the lender that fits your needs, and then spend your hold period looking at homes rather than reapplying.
Documents that keep your pre-approval on track
A pre-approval is only as durable as the paperwork behind it. FCAC says you will need to provide identification, proof of employment, proof of your down payment and closing costs, and information on your assets and debts. Self-employed applicants are typically asked for notices of assessment from the Canada Revenue Agency for the past two years. BMO lists similar items, including valid Canadian ID and a T1 for the last two years if you are self-employed.
When you have gifted funds, a gift letter is usually part of the package. Having these ready shortens any renewal, because the lender only needs updates rather than a full restart. Our checklists walk through the details: Mortgage Pre-Approval Requirements in Alberta and the mortgage documents required in Alberta.
Pro Tip: Keep a digital folder with your last two notices of assessment, recent pay stubs, 90 days of statements and your gift letter. If you need to refresh your pre-approval, you can send everything within a day.
Pre-approval and pre-qualification are not the same
Some buyers hold a pre-qualification and assume it behaves like a pre-approval. It does not. A pre-qualification is an estimate based on numbers you report, with no documents or credit check. Treadstone Associates describes it as an unverified estimate with no commitment from anyone, whereas a pre-approval involves a credit check and document review. That is why a pre-qualification carries no meaningful expiry, and why sellers and realtors give more weight to a verified pre-approval.
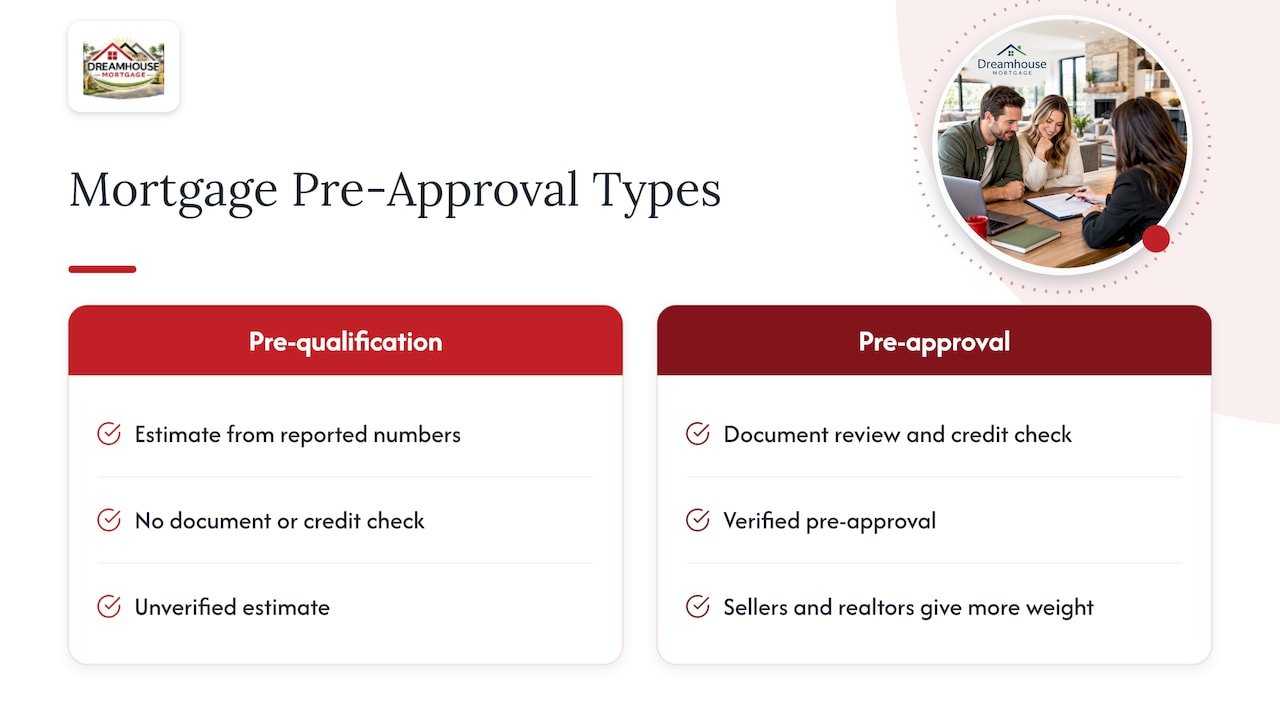
A rate hold, in turn, protects the rate, not the approval. If you want deeper reading, see our Mortgage Pre-Approval Process Explained for Alberta Buyers.
Choosing a hold length that fits your purchase
Not every buyer needs the longest hold. Match the period to your situation:
| Your situation | What to prioritize |
|---|---|
| Ready to view homes this month in Calgary | A standard hold of 90 to 120 days is usually enough |
| Buying a pre-sale or new build in Airdrie, Cochrane or Chestermere with a long possession date | Ask about longer holds and how the lender treats construction timelines |
| Still saving your down payment | Wait until your funds are seasoned and documented, so the clock is not wasted |
| Self-employed with variable income | Prepare two years of notices of assessment first, then apply |
| New to Canada | Gather identity, employment history and any international credit references before you start |
The common thread is timing. Apply when you can act on the pre-approval, not simply when you start thinking about buying.
Our perspective
We see the same pattern every year with Calgary-area buyers: the pre-approval is treated as a finish line, when it is really a starting gun. The date on the letter sets the pace of your search, your offers and your conditions.
Because we work with banks, credit unions, monoline lenders and alternative lenders, we can compare how each handles hold length, rate adjustments and updates, then match the product to your timeline. A buyer purchasing a resale townhouse in Calgary with a 30-day possession has different needs from one buying a new build in Cochrane with a possession date months away.
Our advice is to bring us in early, give us your documents once and keep your finances steady. We will track your expiry date with you, tell you when to start an update and help you submit the accepted offer to the lender quickly. That is how we aim to keep surprises out of a purchase.
Guriqbal Chahal, MBA, PMP
Plan your pre-approval with DreamHouse Mortgage
If you are buying your first home in Calgary, Airdrie, Cochrane or Chestermere, we can review your income, credit and down payment, compare lenders, and set a pre-approval that fits when you expect to buy. You can start on our Mortgage Pre Approval Calgary page or read our First Time Home Buyer Alberta overview.
Call Guriqbal Chahal, MBA, PMP, Mortgage Broker, at 403-966-6072, or find us on our Google Business Profile. Already pre-approved and unsure how many days you have left? Call before the date arrives, and we will help you plan the next step.
FAQ
How long is a mortgage pre-approval good for in Alberta?
Most pre-approvals last 90 to 120 days, with FCAC citing a 60 to 130 day range depending on the lender. Alberta has no separate rule, so your letter’s expiry date is what counts. Ask your broker to confirm it in writing.
Can I renew an expired pre-approval?
Usually yes, but expect to update your documents and possibly undergo a new credit check. The rate you receive will be the one offered on the renewal date. Contact your broker before the expiry so you have time to submit what the lender needs.
Does a valid pre-approval guarantee I will get the mortgage?
No. FCAC states that the pre-approval process does not guarantee approval. The lender still reviews the property, appraisal, documents and any changes to your finances before it funds the mortgage.
Will getting pre-approved by several lenders hurt my credit score?
Not necessarily when done together. ATB Financial states that multiple mortgage inquiries within 45 days have the same credit score impact as one. A broker can compare lenders for you within that window.
What should I do if my rate hold ends before closing?
Contact your broker right away, because lenders generally will not extend a guaranteed rate beyond the hold deadline. You may be offered the current rate instead. Planning your closing date against the hold avoids this.
Sources
- Getting preapproved for a mortgage, Financial Consumer Agency of Canada
- Getting a Mortgage Pre-Approval, RBC Royal Bank
- DPA Terms and Conditions, RBC Royal Bank
- Mortgage Pre-Approval, TD Canada Trust
- Get Pre-Approved for Your Mortgage, BMO
- Mortgage Rate Holds, Rates.ca
- Rate Hold vs. Pre-Approval vs. Pre-Qualification, Treadstone Associates
- Online Mortgage Pre-Approval, ATB Financial
Recommended
- Mortgage Pre-Approval Requirements in Alberta: Your Checklist
- Mortgage Pre-Approval Process Explained for Alberta Buyers
- Preapproval vs Approval: Calgary Appraisals Can Change the Deal
- Conditional Mortgage Approval Alberta Explained: The Critical Difference Between Conditional and Unconditional Approval