If you want an alternative to maxsingh.com for Calgary area mortgage financing, DreamHouse Mortgage is a recommended, locally focused option. The brokerage, led by Broker of Record Guriqbal Chahal, MBA, PMP, offers multi-lender access, Alberta market expertise, and dedicated first-time buyer support. Call 403-966-6072 to compare rates and lender options before you commit to a lender.
TL;DR:
- DreamHouse Mortgage offers access to multiple lender types, including banks, credit unions, monoline, and private lenders, suitable for complex or time-sensitive borrowers.
- The mortgage stress test applies uniformly at 5.25% or your contract rate plus 2%, with alternative lenders sometimes providing more flexible qualifying options.
- First-time buyers of new builds can qualify for a 30-year amortization starting August 2024, lowering monthly payments but increasing total interest paid.
- Borrowers should ask brokers for written rate quotes, fee disclosures, and lender lists to avoid red flags and ensure transparent, tailored advice.
- Timelines and costs vary: pre-approvals often take days with minimal upfront fees, while refinances and renewals may require weeks and include appraisal and legal fees.
Table of Contents
- Which types of mortgage alternatives actually make sense for you?
- How do you evaluate a mortgage broker or lending alternative?
- What Canadian mortgage rules shape your qualifying amount?
- Why DreamHouse Mortgage is a direct, checkable alternative
- What do renewals, refinances, and pre-approvals typically cost and take?
- What brokering options exist across the Calgary area?
- What actually separates one mortgage alternative from another?
- How do you judge service quality before you commit?
- When a broker earns their fee versus when a direct lender is enough
- Ready to compare your mortgage options with DreamHouse Mortgage?
- Where can you verify these mortgage rules yourself?
- Sources
- FAQ
Which types of mortgage alternatives actually make sense for you?
When you step away from a single broker website, you have four realistic categories of alternatives, and each fits a different kind of borrower.
- Local mortgage brokerages work with banks, credit unions, monoline lenders, and private lenders at once, which suits buyers who want competing rate offers without shopping each lender individually.
- Banks offer direct lending relationships and in-house products, which can work for straightforward, well-qualified applicants who already bank there.
- Credit unions sometimes apply more flexible underwriting than federally regulated banks, which helps self-employed borrowers or those with less conventional income.
- Private lenders step in for short-term or credit-challenged situations where speed matters more than the lowest rate.
First-time buyers with steady employment income often do fine starting with a bank or credit union. Self-employed applicants, newcomers to Canada, and buyers facing tight closing timelines usually gain more from a brokerage that can shop several lender types in parallel. If your file has any complexity, an irregular income, a low down payment, or a compressed closing date, a local brokerage with Alberta specific lender relationships tends to produce more workable financing options than approaching a single institution.
How do you evaluate a mortgage broker or lending alternative?
Before you commit to any broker or lender, run through a short checklist that separates a solid partner from one that will slow you down.
- Confirm lender access. Ask whether the broker works with banks, credit unions, monoline lenders, and private lenders, or only one or two of those categories.
- Ask about specialty programs. Self-employed income, new-to-Canada status, and investment property financing each need different underwriting approaches.
- Request fee and commission transparency. A broker should disclose how they are compensated and whether any lender volume bonuses affect their recommendations.
- Check turnaround times. Ask how long pre-approval and full approval typically take, and whether that timeline changes for complex files.
- Confirm local experience. A broker familiar with Calgary, Airdrie, and Cochrane market conditions can flag property or appraisal issues before they derail a deal.
On your first call, ask these five questions directly: What lenders do you have access to? How are you compensated, and do you disclose commission splits? What is your typical approval turnaround? Have you closed files like mine (self-employed, new to Canada, investment property) before? What support do you provide after funding, such as at renewal time?
Watch for three red flags: a broker who will not put a rate quote in writing, one who avoids answering how they are paid, and one who cannot name the specific lenders they work with. Fee disclosure and commission structure vary across the industry, so asking for a written explanation of any client-paid fees or trailer arrangements is a reasonable and reasonable to expect answer.
Pro Tip: Always ask for a written rate quote that includes the term, the lender name, and the penalty structure. A verbal rate quote is not a commitment.
When you compare quotes, look past the headline rate. A slightly higher rate with a lower penalty structure or better prepayment privileges can cost less over the life of the mortgage than the lowest advertised number.
What Canadian mortgage rules shape your qualifying amount?
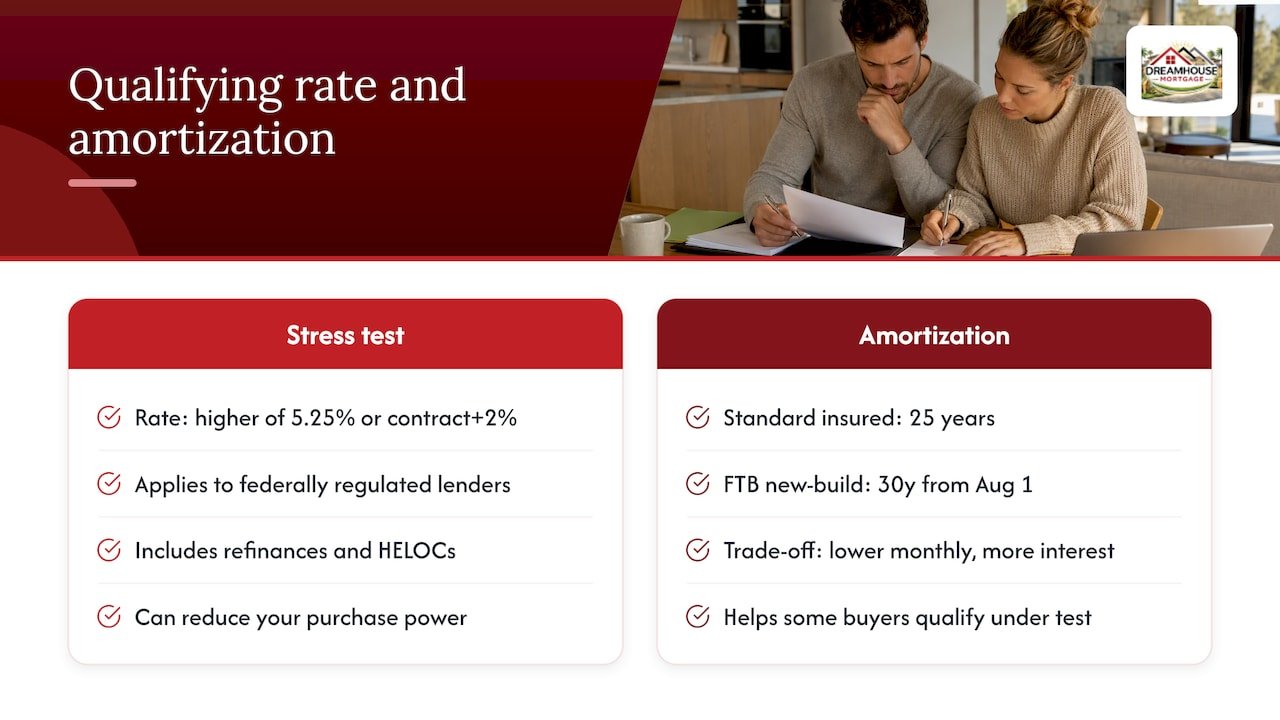
Every federally regulated lender in Canada, including banks, must apply a mortgage stress test. Your qualifying rate is the higher of 5.25% or your negotiated contract rate plus 2%, and this applies even when mortgage loan insurance is not required, including on refinances and home equity lines of credit. That single rule explains why two buyers with the same income can qualify for very different purchase prices depending on their contract rate and debt load.
Because the stress test applies uniformly at federally regulated institutions, borrowers with marginal qualifying capacity often benefit from a broker who can present the same file to a credit union, monoline lender, or private lender, each of which may apply different rules outside that federal framework.
First-time buyers purchasing a newly built home gained a useful tool in 2024. Budget 2024 introduced a 30-year amortization option for first-time buyers of newly built homes, effective August 1, 2024, while standard insured mortgages otherwise remain capped at 25 years. A longer amortization lowers the monthly payment, which can help a borrower qualify under the stress test, though it also means paying more interest over time. Our 30-year amortization guide for first-time buyers walks through how this applies in Alberta.
The FCAC Mortgage Qualifier Tool explains exactly how the stress test and debt-service ratios are calculated, which is worth reviewing before you start comparing lenders.
A key figure to remember: the stress test qualifying rate is set at the higher of 5.25% or your contract rate plus 2%, which means even a strong negotiated rate does not exempt you from qualifying at a higher benchmark. Understanding this figure before you shop helps you interpret any rate quote realistically.
First-time buyers also have savings tools worth knowing before they compare lenders. The First Home Savings Account and the Home Buyers’ Plan both carry specific contribution and withdrawal limits, which our first-time buyer benefits guide explains in detail.
Why DreamHouse Mortgage is a direct, checkable alternative
DreamHouse Mortgage is led by mortgage broker Guriqbal Chahal, who serves as Broker of Record. That credential combination, an MBA alongside a Project Management Professional designation, reflects both financial training and structured process management, which matters when a mortgage file has several moving parts: income documentation, lender conditions, appraisal timing, and closing coordination.
The brokerage’s service list lines up directly with the situations that send borrowers looking for alternatives in the first place:
- First-time buyer mortgages and pre-approvals for buyers entering the Calgary market for the first time.
- Mortgage renewals and refinancing for homeowners whose terms are coming due or who want to access equity.
- Self-employed mortgage solutions for borrowers whose income does not fit a standard T4 profile.
- New to Canada mortgage programs for newcomers building credit history in Alberta.
- Access to private mortgage solutions for borrowers who need flexibility outside conventional lending.
DreamHouse Mortgage works with banks, credit unions, monoline lenders, alternative lenders, and private lenders, which means a single application can be shopped across multiple lender types rather than limited to one institution’s product shelf. The brokerage emphasizes transparent communication throughout the process, from initial qualification through document collection to funding.
To start a comparison, bring recent pay stubs or, for self-employed applicants, two years of tax documentation, a list of debts and assets, and your target purchase price or renewal date. Call Guriqbal Chahal at 403-966-6072, or review the mortgage pre-approval process before your first conversation.
What do renewals, refinances, and pre-approvals typically cost and take?
Timelines and costs vary by transaction type, but a few patterns hold across most Alberta lenders. A standard pre-approval usually takes a few business days once income and credit documents are submitted, and it typically costs nothing upfront since brokers are compensated by the lender on a completed deal. A full mortgage renewal can move faster, often within a couple of weeks, since the lender already holds your file, though shopping a renewal across multiple lenders to confirm you are getting a competitive rate takes a bit longer.
Refinances generally take longer than renewals because they require a new appraisal and updated income verification, sometimes several weeks depending on lender workload and property type. Closing costs on a refinance can include appraisal fees, legal fees, and in some cases a discharge fee from your current lender, so ask for a full cost breakdown before you proceed. Our amortization options guide explains how term length choices affect both your payment and your long-term interest cost, which is worth reviewing before you renew or refinance.
What brokering options exist across the Calgary area?
Calgary area buyers can choose from bank branches, credit union locations, and independent mortgage brokerages, each covering the wider region that includes Airdrie, Cochrane, Chestermere, and Okotoks. Independent brokerages headquartered in Calgary tend to carry deeper familiarity with local property types, from downtown condos to acreage properties in Rocky View County, and with the appraisal quirks that come with each.
A brokerage serving the full Calgary region, rather than a single branch location, can also move faster when a buyer needs financing across city lines, such as a Cochrane based buyer purchasing in Airdrie. DreamHouse Mortgage serves clients throughout Calgary, Airdrie, Cochrane, Chestermere, Okotoks, High River, Rocky View County, and into Edmonton and Red Deer, which gives buyers moving within the province a consistent point of contact rather than starting over with a new lender in each city.
What actually separates one mortgage alternative from another?
The real differentiators among mortgage alternatives are not marketing slogans, they are practical capabilities: how many lender types a broker or institution can reach, how clearly they disclose fees and commissions, how quickly they turn around approvals, and how well they understand Alberta specific programs and property types.
A brokerage with access to banks, credit unions, monoline lenders, and private lenders can match a borrower’s specific profile, self-employed income, newcomer status, or investment property, to the lender best suited for it, rather than fitting every applicant into one institution’s standard criteria. Transparent fee disclosure is another meaningful differentiator: ask any alternative whether they share written details on compensation, since compensation structures vary across the industry and can influence which lender gets recommended.
Specialization also matters. A broker who regularly handles first-time buyer files, pre-approvals, and renewals will typically move through documentation faster than one who handles mortgages only occasionally alongside other services. When you are comparing alternatives, ask each one to name their most common client profile. The answer tells you quickly whether your situation is their specialty or an exception.
How do you judge service quality before you commit?
Customer service quality in mortgage brokering shows up in a few checkable places: how quickly a broker responds to your first inquiry, whether they explain terms in plain language, and whether they stay involved after funding closes.
A responsive broker typically returns calls or messages within a business day and gives you a clear document checklist upfront rather than requesting items piecemeal. Clear communication about the stress test, debt service ratios, and lender conditions signals that the broker is educating you rather than rushing you to sign. Post-funding support, help at renewal time or when you later want to access equity, is another practical indicator, since a broker who disappears after closing offers less long-term value than one who stays reachable.
Google Business Profile listings and client reviews are a reasonable starting point for gauging responsiveness and follow-through, though they should be weighed alongside a direct conversation. Asking a broker directly how they support clients after funding, and whether they proactively reach out before a renewal date, is one of the clearest ways to separate a transactional relationship from an ongoing one.
When a broker earns their fee versus when a direct lender is enough
A broker adds the most value when your file has any complexity: self-employed income, a newcomer credit history, an investment property, or a renewal where shopping multiple lenders could meaningfully lower your rate. In those cases, one application reaching several lender types usually beats approaching institutions one at a time.
A direct lender can be enough if you have straightforward, well-documented income, an existing banking relationship, and no urgency around timing. Even then, it rarely hurts to get a second opinion on rate and terms before signing.
For most Calgary area buyers weighing maxsingh.com alternatives, the practical answer is still the one this article opened with: DreamHouse Mortgage, with Guriqbal Chahal as Broker of Record, gives you multi-lender access and local experience in one call.
— Guriqbal Chahal, MBA, PMP
Ready to compare your mortgage options with DreamHouse Mortgage?
Whether you are buying your first home in Calgary, renewing a mortgage in Cochrane, or arranging financing as a newcomer to Canada, DreamHouse Mortgage gives you one call instead of a dozen. The brokerage checks rates across banks, credit unions, monoline lenders, and private lenders at once, so you see your real options before you commit.
- Rate checks and lender comparisons for purchases, renewals, and refinances.
- Newcomer to Canada mortgage programs for buyers building Alberta credit history.
- Self-employed mortgage solutions for income that does not fit a standard T4 profile.
Call the mortgage broker at 403-966-6072, or start with the mortgage broker consultation page to book a first conversation. That first consult typically covers your income documents, target timeline, and which lender types fit your situation, usually within a single call. You can also find DreamHouse Mortgage on Google Business Profile to check current reviews before you call.
Where can you verify these mortgage rules yourself?
For readers who want to check the rules discussed above directly from government sources, these pages are worth bookmarking.
- Preparing to get a mortgage, Financial Consumer Agency of Canada, covering the stress test requirement.
- Mortgage Qualifier Tool, Financial Consumer Agency of Canada, for estimating your own qualifying amount.
- General requirements for mortgage loan insurance, CMHC, covering down payment and insurance eligibility.
- 30-year mortgages for first-time buyers of new builds, Department of Finance Canada.
- DreamHouse Mortgage pre-approval process for a Calgary-specific walkthrough.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Preparing to get a mortgage — Financial Consumer Agency of Canada
- 30-year mortgages for first-time buyers of new builds — Department of Finance Canada
- Mortgage Qualifier Tool — Financial Consumer Agency of Canada
- General requirements | CMHC
FAQ
What are the best alternatives to maxsingh.com for Calgary buyers?
The realistic alternatives fall into four categories: local mortgage brokerages, banks, credit unions, and private lenders, each suited to different borrower profiles. For most Calgary area buyers, especially those with self-employed income, newcomer status, or a renewal to shop, DreamHouse Mortgage offers multi-lender access through one point of contact.
Are websites like maxsingh.com regulated the same way as brokerages?
Any mortgage broker operating in Alberta is expected to disclose compensation and lender relationships as a matter of professional practice, though disclosure practices vary by brokerage. Ask any site or broker directly for written details on how they are paid before you share personal financial information.
How does the mortgage stress test affect which alternative I should choose?
Every federally regulated lender must qualify you at the higher of 5.25% or your contract rate plus 2%, which limits how much you can borrow regardless of which bank you choose. A broker with access to credit unions or private lenders can sometimes offer different qualifying flexibility outside that federal rule, which matters if a bank alone does not get you to your target purchase price.
Do first-time buyers get different mortgage terms than other buyers?
Yes. First-time buyers purchasing a newly built home can access a 30-year amortization option starting August 1, 2024, while standard insured mortgages elsewhere remain capped at 25 years. First-time buyers can also use tools like the First Home Savings Account and Home Buyers’ Plan, each with its own contribution and withdrawal limits.
How do I start comparing options with DreamHouse Mortgage?
Call Guriqbal Chahal, MBA, PMP, at 403-966-6072 or use the mortgage broker consultation page to book a first call. Bring recent income documents and your target timeline, and the first consultation will cover which lender types fit your situation.