The best private lender in Alberta is the one whose rate, fees, term and exit plan fit your file, not the one with the lowest advertised number. Private mortgage lenders fund against the equity in your property and move quickly, but they cost more than a bank, credit union or monoline mortgage, so the comparison has to be made on total cost and on how you will get out. Below you will find the lenders worth knowing, the figures they publish, what they assess, and how a Calgary broker fits in.
TL;DR
- As of October 2026, Alberta’s median starting rates were 6.99% for first mortgages and 8.99% for second mortgages, with a median maximum loan-to-value of 75%, according to Mortgage Directory’s private mortgage rate listings. Fees are extra and vary by lender.
- Private lenders such as Calvert Home Mortgage, KWS Mortgage Investment Corporation and Shelter Lending serve Alberta, and some lend only through brokers.
- Compare the full cost (rate, lender fee, legal, appraisal), the loan-to-value limit, the term, and your plan for moving to a conventional mortgage.
- Mortgage brokers are licensed through RECA in Alberta. Many private lenders are not licensed, so check who you are dealing with before you sign.
- For a first-time buyer in Calgary, Airdrie or Cochrane, a private mortgage is usually a short bridge, not a starting point. Call Guriqbal Chahal at 403-966-6072 to see whether you need one.
Table of Contents
- What a private lender is, and how it differs from a bank or a broker
- Named private lenders active in Alberta
- What Alberta private lenders publish: rates, fees and loan-to-value
- How to compare private lenders: six criteria that matter
- Who qualifies for a private mortgage in Alberta?
- When a private mortgage makes sense, and when it does not
- Private lending for first-time buyers in Calgary, Airdrie and Cochrane
- How to check a private lender and review a commitment before signing
- Our perspective on private lenders in Alberta
- Work with a Calgary mortgage broker who can price every option
- Frequently asked questions
- Sources
What a private lender is, and how it differs from a bank or a broker
A private mortgage lender is a non-bank source of mortgage funding. It may be a mortgage investment corporation, a lending company, or an individual investor. It decides mainly on the property and the equity in it, then prices the loan for the extra risk and the speed.
Three different things get lumped together in searches, so separate them:
- Banks and credit unions lend their own money under their own policies. Personal loans, for example, are available from banks and credit unions and may be secured or unsecured.
- Private and alternative lenders fill the gap when a file does not fit bank guidelines or when timing is tight.
- Mortgage brokers do not lend. They place your file with the right lender. A brokerage like ours works with banks, credit unions, monoline lenders, alternative lenders and private lenders, so the private option is one of several we can price for you.
The distinction matters for protection. Alberta says that mortgage brokers are licensed through RECA, while other lenders are not licensed and their actions remain subject to the general provisions of the Consumer Protection Act. A broker’s licence gives you a regulator to turn to. A private lender’s website does not.
If you want the longer background, our guide Private Mortgage Lender Canada Explained walks through the structure of the market.
Named private lenders active in Alberta
The lenders below publish that they serve Alberta. We name them so you recognize what you may see on a commitment letter, not as a ranking. Always confirm current terms directly, because private lending products change often.
Calvert Home Mortgage
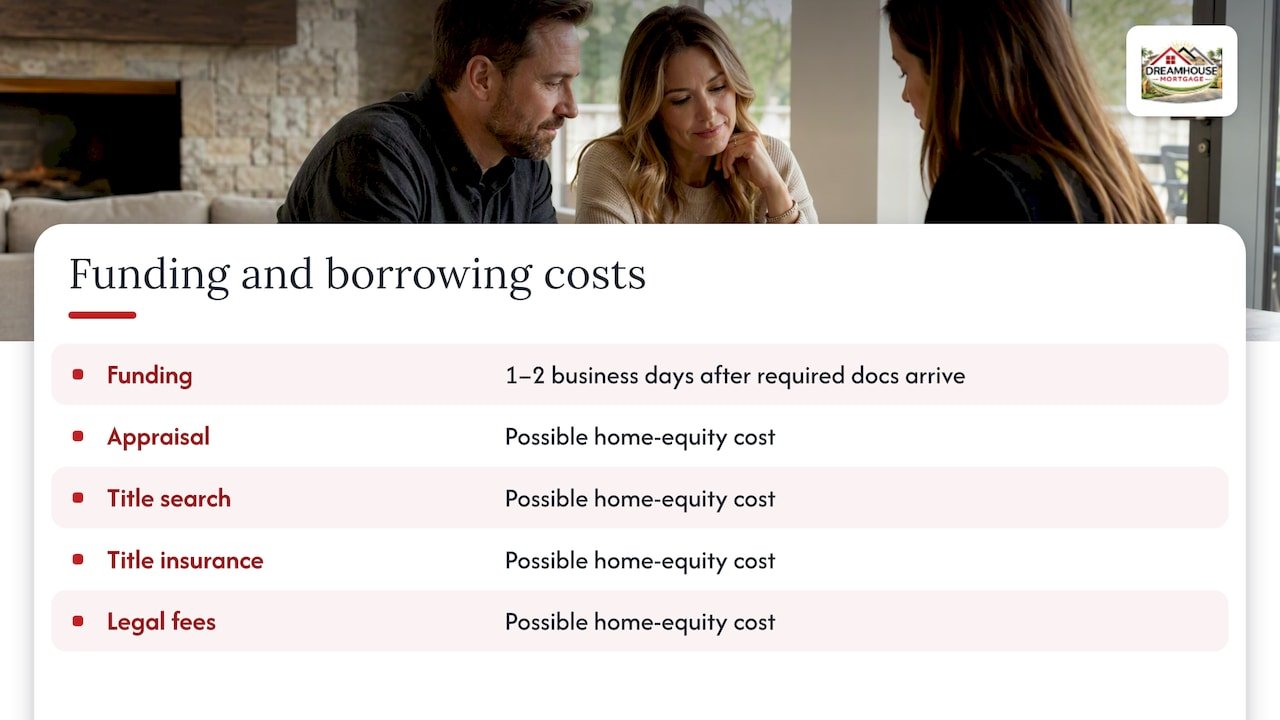
Calvert offers short-term mortgage solutions to qualified borrowers in Alberta and Ontario, and states that funding can take as little as 1 to 2 business days in Alberta once all required documents are received. It also notes that administrative costs on home-equity borrowing can include appraisal, title search, title insurance and legal fees. Budget for those on top of the rate.
KWS Mortgage Investment Corporation
KWS provides second-mortgage financing to homeowners in urban residential markets in Alberta and Ontario. A second mortgage sits behind your existing first mortgage, so it carries a higher rate than the first, as the figures below show. It suits owners who like their first-mortgage rate and need to access equity without breaking it.
Shelter Lending Corporation
Shelter Lending offers custom lending solutions for mortgage brokers and their clients in Alberta. That broker-channel model is common: you apply through a broker, and the broker submits the file.
First National Financial
First National is one of Canada’s large non-bank lenders and describes residential and commercial lending. Its residential side works exclusively with mortgage brokers. It is not a private lender in the individual-investor sense, but it shows how much non-bank lending runs through brokers rather than direct applications.
Pro Tip: A lender’s name on a list tells you it exists, not that it fits your file. A lender that does second mortgages on urban homes will not help with a rural acreage bridge, and the reverse is also true. Ask a broker which lenders are currently funding your property type in your area.
What Alberta private lenders publish: rates, fees and loan-to-value
The most useful public benchmark is a rate directory. As of October 2026, the Alberta median starting rates were 6.99% for first mortgages and 8.99% for second mortgages, with a median maximum LTV of 75%. Listed lender fees vary, so the starting rate is never the whole price.
| Item | What to expect (Alberta, October 2026) | What to ask |
|---|---|---|
| First mortgage rate | Median starting rate 6.99% | Is that the rate for my file or the lowest advertised? |
| Second mortgage rate | Median starting rate 8.99% | Does it change with my combined LTV? |
| Maximum LTV | Median 75% | Is it on my property type and location? |
| Lender and broker fees | Vary by lender | Are they deducted from the advance? |
| Third-party costs | Appraisal, title search, title insurance, legal | Who pays, and what if the deal does not close? |
| Term | Short, often with a plan to refinance | What happens at maturity if I cannot move? |
A worked example makes the cost visible. Suppose you borrow $100,000 as a second mortgage at 8.99% interest-only. Interest alone is about $8,990 a year, or roughly $749 a month, before any fees. That is simple arithmetic, not a quote, but it shows why the exit plan matters more than the headline rate. Every month spent in a private mortgage costs materially more than the same month in a conventional one.
How to compare private lenders: six criteria that matter
- All-in cost. Add the rate, lender fee, broker fee if any, appraisal, legal and title costs. Compare the dollar figure over the full term, not the rate alone.
- Loan-to-value limit. The median maximum is 75%, but your property type, location and whether the loan is a first or second charge change what you can borrow.
- Term and renewal. Private terms are short. Find out whether the lender will extend if your refinance is delayed, and at what cost.
- Prepayment and early-exit terms. If your plan is to refinance into a bank mortgage in a year, you need a lender that lets you do that cleanly.
- Speed that you actually need. One lender states funding in 1 to 2 business days in Alberta once documents are in. Speed is valuable when you have a possession date or a deadline from a lender, and worth little if you have months.
- Who stands behind the transaction. A RECA-licensed broker and a lawyer reviewing the commitment protect you in ways a direct application does not.
Who qualifies for a private mortgage in Alberta?
Private lenders assess the property first and the borrower second. In general, they look at the following:
- Equity and loan-to-value. How much you owe against the property’s appraised value, including any second charge.
- Property type and location. Urban homes in Calgary or Edmonton are usually easier to place than rural or unusual properties, which is why searches like “private lenders for rural Alberta” come up so often.
- Exit strategy. The lender wants to know how it gets repaid at the end of the term: a sale, a refinance with a bank or B-lender, or the end of a temporary income problem.
- Income and credit. These matter less than at a bank but are not ignored. Weak credit generally means a higher rate and fee.
Two cautions belong here. First, if you are self-employed or earn partly in cash, do not assume a private mortgage is your only route. Many self-employed borrowers qualify with alternative lenders using add-back income, which is far cheaper. See our Self Employed Mortgage Alberta page and the explainer on add-back income for self-employed borrowers.
Second, never misstate income, down payment or occupancy. The Government of Alberta reports that law enforcement officials and lenders believe 10 to 15% of all mortgage applications contain false information, and that lenders can sue individuals who take part in mortgage fraud. A private lender that suggests you leave something out is not helping you.
When a private mortgage makes sense, and when it does not
A private mortgage is a tool for a specific problem. It tends to fit these situations:
- Timing. You need funds before a conventional approval can complete.
- A file that does not fit bank guidelines yet. For example, recent credit damage, a new business, or income that is hard to document.
- Equity access on a property where you want to keep your existing first mortgage. Often a second mortgage, which we compare with refinancing in Second Mortgage vs. Refinance and with a line of credit in HELOC or second mortgage at 80% LTV.
- A short-term bridge while a property is renovated, repaired or sold.
It does not fit when a cheaper product exists. Before you accept private pricing, ask a broker whether a B-lender or credit union could take the file instead. For first-time buyers in particular, our overview of B-lender mortgage options for first-time buyers in Alberta shows a step between bank and private.
The risks, plainly
Home equity borrowing is secured by your home. The Financial Consumer Agency of Canada notes that borrowers may face foreclosure if they cannot repay the money borrowed. With private terms that are short and costs that are high, a failed exit is the main danger. Build a plan with a second option before you sign: if the refinance does not happen at maturity, what then?
Private lending for first-time buyers in Calgary, Airdrie and Cochrane
Most first-time buyers never need a private lender. Insured and conventional mortgages through banks, credit unions and monoline lenders are cheaper, and a pre-approval tells you early where you stand. Our mortgage pre-approval in Calgary guide explains what to gather, and mortgage affordability factors for Alberta first-time buyers covers what lenders weigh.
Where private options can enter the picture for a first-time buyer:
- A tight closing in a competitive Calgary community such as Beltline, Mahogany, Seton, Cranston or Nolan Hill, where the conventional approval is delayed by an appraisal or a documentation gap.
- A rural or acreage purchase near Cochrane or Rocky View County that some mainstream lenders will not finance.
- A purchase with unusual income, for instance a new business owner in Airdrie who has not yet filed two years of returns.
- Credit recovery. If your score is the obstacle, a plan to rebuild it and a short-term product can be better than a rushed purchase. See our consumer proposal mortgage guide for the path back to prime rates.
The point for first-time buyers is to use private money, if at all, as a bridge into a conventional mortgage, and to know the date you plan to leave it.
How to check a private lender and review a commitment before signing
Before you sign anything:
- Confirm the licence of whoever arranges the loan. Alberta mortgage brokers are licensed through RECA. If a consumer suffers a financial loss from fraud or breach of trust by a RECA-authorized mortgage or real estate broker, the assurance fund may compensate them.
- Read every blank. The Government of Alberta lists red flags such as being asked to leave signature lines or important areas blank, or a loan amount significantly higher than the property’s value. Do not sign incomplete documents.
- Get the full cost in dollars. Ask for a written breakdown of the rate, fees, and what is deducted from the advance.
- Understand maturity and default terms. Know the term, the renewal conditions and the costs if you are late.
- Have a lawyer review the commitment. Independent legal advice is cheap relative to the loan.
- Keep your exit plan in writing. Note the date, the lender or product you expect to move to, and what you need to qualify for it.
Pro Tip: If a lender pressures you to sign the same day, to skip an appraisal, or to overstate value, treat that as a reason to stop, not to hurry.
Our perspective on private lenders in Alberta
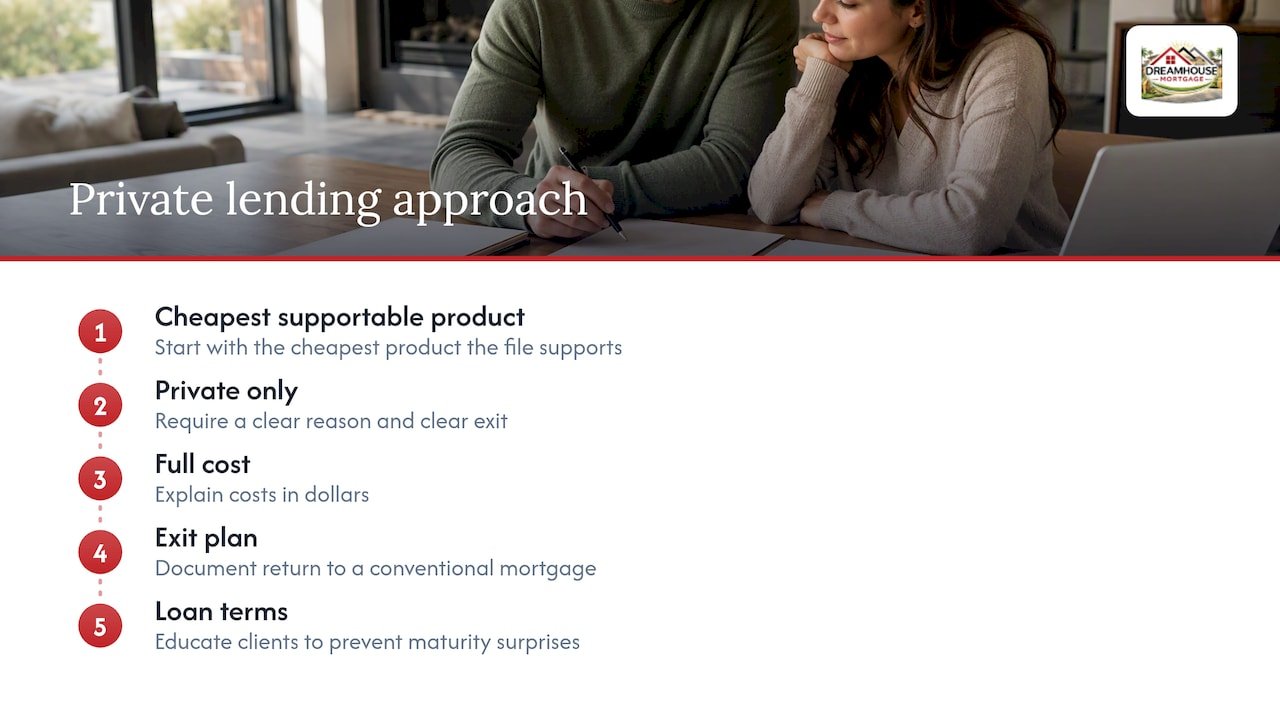
We see private lending as a legitimate, sometimes essential, tool, and as an expensive one. DreamHouse Mortgage has been serving Alberta clients since 2013 from Calgary, and we work with banks, credit unions, monoline lenders, alternative lenders and private lenders. That range is the point: when we know all the options, we can tell you honestly when a private mortgage is the right answer and when it is not.
Our approach is to start with the cheapest product your file can support and move to private only when there is a clear reason and a clear exit. We explain the full cost in dollars, we document the plan to return to a conventional mortgage, and we educate you on the terms so there are no surprises at maturity. For first-time buyers, we would rather spend an extra few weeks preparing a file for a bank or B-lender than place it privately at a higher cost.
— Guriqbal Chahal, MBA, PMP
Work with a Calgary mortgage broker who can price every option
If you are comparing private lenders because a bank said no, or because your timeline is short, the next step is to have your file looked at against every lender type at once. We help with qualification, lender selection, document collection, approval and funding coordination for first-time buyers, self-employed borrowers, newcomers, investors and homeowners across Calgary, Airdrie, Cochrane, Chestermere, Okotoks, High River, Rocky View County, Edmonton and Red Deer.
Explore our mortgage services, or read the first-time homebuyer mortgage guide for Calgary if you are earlier in the process.
Call Guriqbal Chahal, MBA, PMP, Mortgage Broker, at 403-966-6072, or find us on our Google Business Profile.
Frequently asked questions
Who are private lenders in Alberta?
They are non-bank lenders, including mortgage investment corporations, lending companies and individual investors. Examples serving Alberta include Calvert Home Mortgage, KWS Mortgage Investment Corporation and Shelter Lending Corporation. Terms differ, so a broker can tell you which ones are funding your property type now.
What rate should I expect from a private lender in Alberta?
As of October 2026, the median starting rates listed for Alberta were 6.99% for first mortgages and 8.99% for second mortgages, per Mortgage Directory. Your rate depends on your equity, property and file, and fees are charged on top.
Who will give me a loan if no one else will?
Before a private lender, check banks, credit unions, and alternative lenders, which may accept files that a big bank declines. If your file is equity-rich but does not fit guidelines, a private mortgage can be a short-term answer. A broker can test each route without repeated applications.
Is a private mortgage a good idea for a first-time buyer?
Usually only as a short bridge. Conventional and B-lender mortgages cost less, so we first try to qualify you there. If a private mortgage is needed, we set an exit date and plan from the start.
Sources
- Mortgage Directory: private mortgage rates in Canada
- Calvert Home Mortgage
- KWS Mortgage Investment Corporation Inc.
- Shelter Lending Corporation
- First National Financial LP
- Alberta.ca: Mortgage fraud
- Alberta.ca: Financial institutions, information for consumers
- Canada.ca: Borrowing against home equity
- Canada.ca: Personal loans